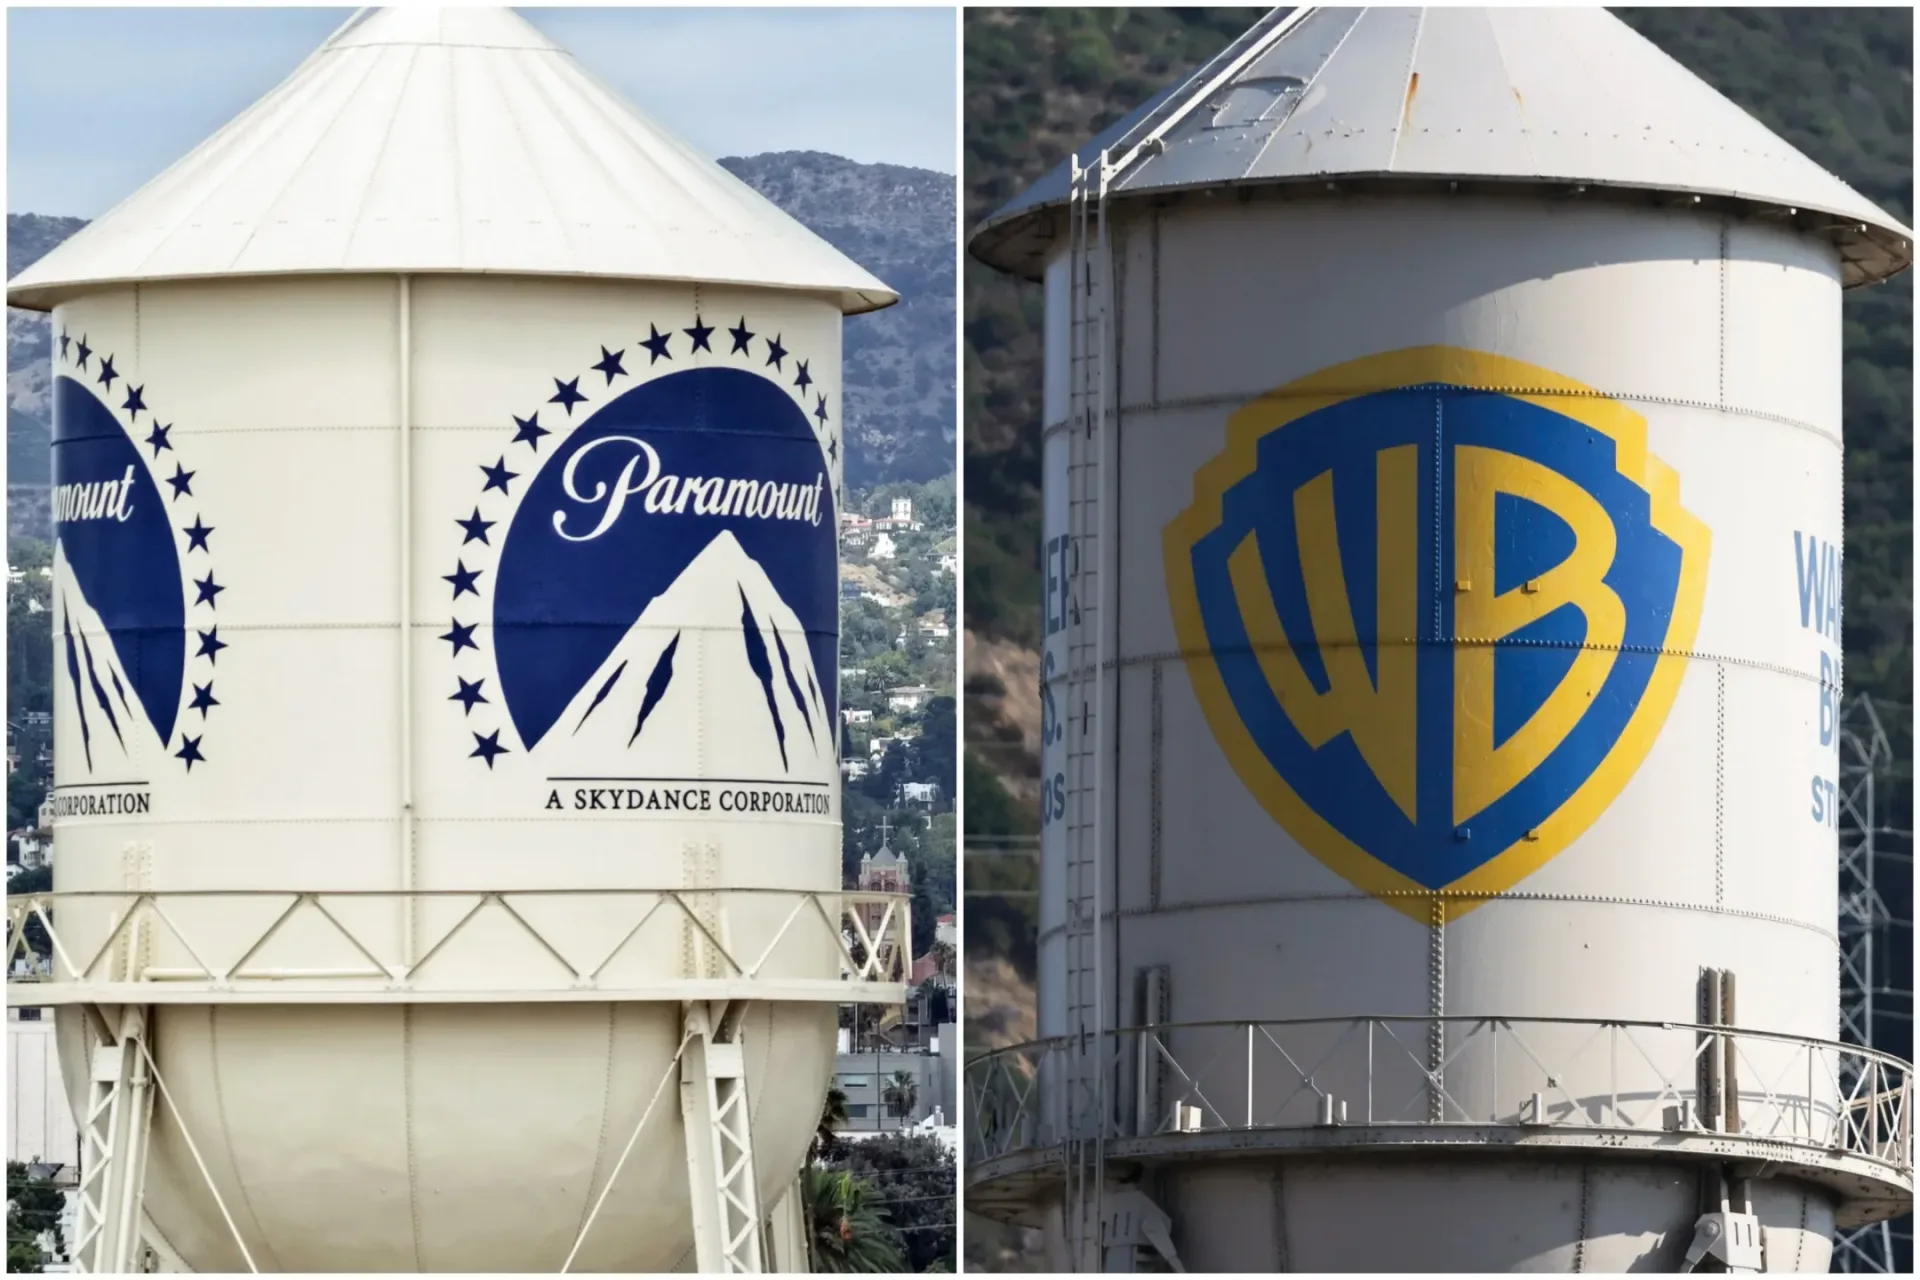
Skydance Corp. has begun its first day as the combined Paramount-Warner Bros. Discovery business with a muted market debut. Trading under the ticker SKYD started on the New York Stock Exchange on Tuesday, following the closing of the merger, and the stock ended regular trading at $9.51 per share, down 2.7%.
The intraday picture was volatile rather than uniformly negative. SKYD was down as much as 6% at one point, briefly moved above its previous reference point, and reached an intraday high of $9.84 before closing lower. One session does not establish the long-term value of a newly combined company, but it does show that the market is immediately focused on the hard parts of the deal: debt, integration, dilution, and whether a larger entertainment group can deliver the savings and growth its backers expect.
David Ellison described the company’s aim as building a stronger competitor that supports creative work, serves audiences and rewards shareholders. That ambition now has to operate alongside a far more concrete investor question: whether the new company can make the combination work while navigating pressure on traditional television, fierce streaming competition and the unpredictable economics of hit-driven entertainment.
What changed for Paramount and Warner Bros. Discovery shareholders
The market transition happened across two exchanges and two former stock listings. Paramount Skydance Class B common stock, previously traded on Nasdaq as PSKY, was withdrawn from the Nasdaq Global Select Market. Trading in PSKY ended at the close on Monday, Oct. 5. SKYD then began trading on the NYSE when the market opened Tuesday.
Warner Bros. Discovery shares also stopped trading on Nasdaq as the transaction closed. WBD shareholders received cash equal to $31.01666668 per share.
For former PSKY holders, the change is more than a ticker swap. Their shares are now tied to the larger Skydance Corp. structure, and a major warrant distribution is scheduled to follow. The upcoming warrants are central to understanding why the first trading price has drawn attention.
The $12 warrants, explained
Skydance’s board set Oct. 13 as the distribution date for 471.3 million warrants. A warrant is a financial instrument that gives its holder the right, but not the obligation, to purchase a company share at a set price before a stated expiration date. It is not itself a share of stock, and holding one does not require an investor to buy the underlying share.
In this case, each warrant gives an eligible holder the option to buy one share of SKYD Class B common stock at an exercise price, also called a strike price, of $12.00. Holders have up to 10 years to exercise those warrants. The company expects to distribute one warrant for every eligible PSKY Class B share held as of Oct. 5.
Related coverage includes Skydance Shares Close Down 2.7% as NYSE Trading Begins After Paramount-WBD Deal.
The key comparison is straightforward: SKYD closed its first NYSE session at $9.51, below the $12 exercise price. That puts the warrants out of the money at that moment. In plain language, it would not make economic sense to exercise a warrant immediately to pay $12 for a share trading at $9.51, because the same share could be purchased in the market for less.
That does not mean the warrants have no possible future value. They last for up to a decade, so their value depends in part on whether SKYD’s share price rises above $12 before expiration. Nor does it mean every holder will make the same choice. The important point is that the first close landed below the threshold at which direct exercise would make sense based on the market price alone.
Why the warrants exist
The warrants are intended to give eligible PSKY shareholders an opportunity to purchase Skydance Class B shares on terms similar to those extended to the equity syndicate behind the Warner Bros. Discovery transaction. That $47 billion equity syndicate included David Ellison, Larry Ellison, RedBird Capital Partners head Gerry Cardinale, LionTree, and sovereign wealth funds from Saudi Arabia, Qatar and Abu Dhabi. Their SKYD equity investments were priced at $12 per share.
Not every outstanding Class B share is included in the distribution. As of Oct. 2, Skydance reported 1,093,020,754 Class B shares issued and outstanding. Roughly 622 million were held by or for restricted holders, the Paramount Global 401(k) plan and the Paramount Global Master Trust; those shares are excluded from the warrant distribution.
If all 471.3 million warrants were exercised and settled, the Class B share count would rise to 1,564,320,754, based on the Oct. 2 share total. This is what investors mean by dilution: more shares outstanding can reduce each existing share’s proportional claim on a company’s equity and future earnings, unless the additional capital and business performance create enough value to offset that effect.
Dilution is not automatically good or bad. It is a structural factor investors must weigh, particularly when a company has a large, defined block of potential future shares linked to a $12 exercise price. The warrants could also bring money into the company if exercised. But the timing, exercise rate and eventual market conditions will matter.
Class A control remains concentrated
The company’s governance structure is another important part of the new setup. The Ellison family and RedBird are the sole holders of Skydance’s Class A stock, and that class carries 100% of the voting control.
That means Class B shareholders can participate economically in the company but do not have equivalent voting power over corporate decisions. Dual-class arrangements are designed to keep control concentrated with specified owners even when a company has broader outside investment. For investors, it is a reminder that the financial interest represented by a Class B share is distinct from control of the business.
In practical terms, the people leading and backing the merger have a durable ability to direct the company’s strategy. That can allow management to pursue a longer integration plan without facing the same voting dynamics as a one-share, one-vote company. It also gives minority shareholders less direct influence over decisions if they disagree with that plan.
Why investors are looking at leverage and integration risk
The share-price movement arrived one day after Fitch Ratings downgraded the new Skydance’s credit rating. The rating firm cited materially higher leverage after the acquisition, meaningful execution and integration risks, and uncertainty about whether the company can achieve the synergies it has identified as necessary for its deleveraging target.
Leverage refers to debt relative to a company’s financial capacity. A highly leveraged company has more borrowing to service, which can make its results more sensitive to shifts in revenue, operating costs and interest obligations. In a merger of this scale, investors commonly scrutinize whether projected cost savings and business gains arrive quickly enough to support the enlarged balance sheet.
Synergies are the expected benefits created by operating two formerly separate businesses together. They can include cost reductions, consolidated operations or improved opportunities to use content across a larger organization. They are projections, however, not automatic results. Achieving them usually requires management decisions, system changes and coordinated operations; those steps can be expensive, disruptive or slower than expected.
Integration risk is the chance that these moving pieces do not combine as planned. It can include the operational challenge of bringing organizations together, the risk that expected savings do not materialize, or the possibility that strategic priorities conflict. Fitch specifically connected the risk to Skydance’s ability to meet its deleveraging goal, meaning its stated plan to reduce debt over time.
The ratings firm also identified structural pressure on linear television revenue, streaming competition and hit-driven content risk. Linear television is conventional scheduled TV programming, as opposed to on-demand streaming. The concern is that a business dependent in part on that model is operating amid industry shifts that can affect audience behavior and advertising or distribution economics.
Hit-driven risk is particularly relevant to entertainment companies: the financial performance of content can be uneven, with major successes carrying disproportionate weight and misses potentially leaving gaps in expected revenue. A bigger library and broader portfolio may create more opportunities, but scale does not erase the uncertainty of whether audiences will choose particular films, shows or franchises.
Analysis: the opening price is a starting signal, not a verdict
It would be premature to treat a 2.7% first-day decline as a final market judgment on the merger. The debut was accompanied by an exchange move, the end of separate WBD trading, a complex warrant structure and a fresh credit-rating downgrade. Those are unusual conditions for any first session, and they give investors several issues to price at once.
Still, the $9.51 close creates a clear early benchmark. It sits below the $12 price attached both to the new warrants and to the equity investments from the deal’s backing syndicate. That makes the path from corporate ambition to shareholder returns more visible: investors will be watching for operating progress that can support confidence in the company’s ability to strengthen its finances, execute the integration and compete across rapidly changing entertainment markets.
The wider lesson for games and entertainment audiences is not that stock movement predicts whether particular creative projects will succeed. It does not. But the corporate structure behind media can shape the resources, priorities and risk tolerance available to the people making and releasing entertainment. For a separate perspective on the practical challenges that come with major creative and technical transitions, Sonic Team’s account of moving Sonic Adventure into 3D illustrates how difficult execution can be even when a strategic direction is clear.
For Skydance, the immediate facts are simpler than the long-term questions: SKYD has started trading, the company is preparing its warrant distribution, and its leadership enters the integration phase with concentrated voting control. The market will now have considerably more than a single trading day to assess whether the combined company can turn its scale into the stronger competitive position its leadership has promised.