Paramount Skydance’s proposed $110 billion acquisition of Warner Bros. Discovery is approaching a consequential decision point. Settlement talks with the coalition of 12 state attorneys general that sued to block the deal have intensified, while opponents are organizing demonstrations in Oakland, Los Angeles and New York to argue against a compromise.
For the companies, the immediate pressure is financial as well as legal. The acquisition agreement reached in late February calls for Paramount to pay Warner Bros. Discovery shareholders an additional $7 million per day starting Oct. 1 if the transaction has not closed. For regulators and critics, however, the central question remains whether conditions attached to a settlement would do enough to address the competition concerns behind the lawsuit.
The dispute has direct relevance for entertainment and games. Warner Bros. Discovery’s streaming-and-gaming business is led by JB Perrette, and any new corporate structure would inevitably place major film, television, streaming and gaming operations under the same overall owner. The available details do not establish what specific changes, if any, would be made to Warner Bros. Discovery’s games business. They do show why the proposed terms of a settlement are receiving unusually close scrutiny.
The last major obstacle to closing
California and New York are among the 12 states that filed the federal antitrust suit in July. That action is described as the final remaining hurdle to completing Paramount Skydance’s agreement to acquire Warner Bros. Discovery.
Antitrust litigation examines whether a transaction could unlawfully reduce competition. A settlement can end litigation without a full trial if the parties agree to remedies: obligations or structural changes intended to resolve the government’s concerns. The difference between the two broad kinds of remedies is at the heart of these negotiations.
- Structural remedies alter ownership or organizational structure. In this matter, California Attorney General Rob Bonta has said genuinely separate ownership would qualify as meaningful separation.
- Behavioral remedies require conduct after a merger, such as operating units separately for a set period, maintaining output commitments, or making job-related pledges.
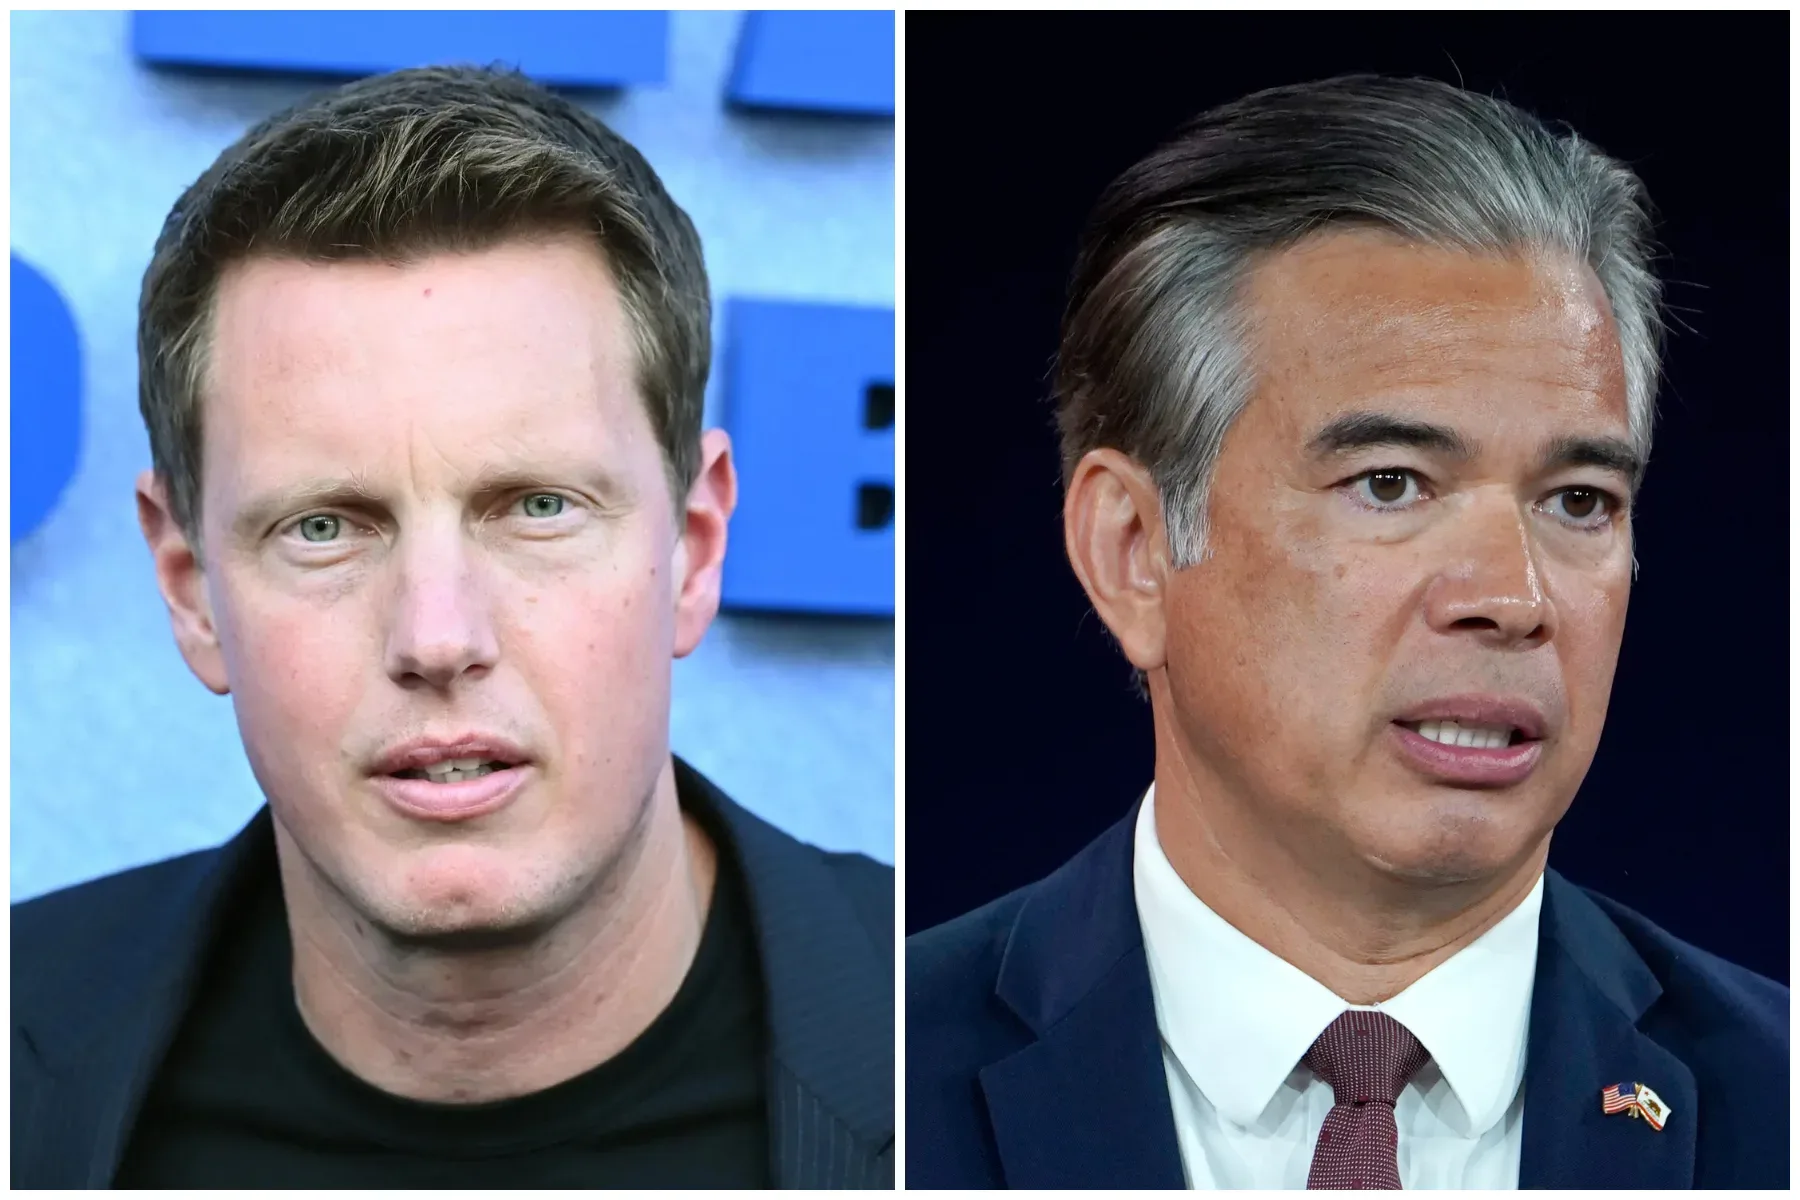
Bonta has repeatedly been skeptical of behavioral remedies, arguing that they are difficult for states to enforce effectively. His position on the question of separate operations is especially clear: separate management or operations under one merged corporate roof is not the same as separate ownership.
“There needs to be separate ownership,” Bonta said. “If it’s under the same Paramount-Warner Bros. merged-entity roof, that’s not separate.”
That distinction matters because a reported pathway toward settlement would involve enforceable commitments for Paramount to keep some or all Warner Bros. Discovery assets operationally separate from Paramount. Such a deal could also include fixed-term job-preservation commitments. It would not necessarily satisfy the stricter standard Bonta has publicly described.
What has reportedly been discussed
Several potential provisions have surfaced during negotiations, but none has been confirmed as a final agreement. Paramount Skydance did not comment on the settlement discussions.
One possibility is that the two studios would remain separate for a period rather than being immediately combined. David Ellison, Paramount Skydance’s CEO, had already offered a version of that commitment in a Feb. 28 letter to California lawmakers Adam Schiff and Laura Friedman. Ellison said he intended to keep both legacy studios operating separately, with the stated goal of preserving and potentially increasing jobs.
That earlier pledge explains why opponents and regulators may see a temporary separate-operations requirement as insufficient on its own. If a company has already publicly committed to a particular course, a settlement term requiring the same conduct may offer less additional protection than a divestiture or separate ownership arrangement. That is an analytical point based on the positions laid out by the parties; the final terms, if any, have not been disclosed.
Negotiators have also discussed production output. Ellison has long pledged to make at least 30 films annually, and that commitment has been part of the conversation. Other ideas under discussion include a written promise to remain in California and a third-party editorial adviser for CNN and CBS.
These provisions concern different risks. Film-output and job commitments address creative work and employment. A California commitment concerns the location of operations. An editorial adviser relates to news organizations. None directly specifies a plan for gaming, but they illustrate the broader challenge of designing obligations across a conglomerate that spans multiple entertainment businesses.
Why entertainment and games watchers should pay attention
Warner Bros. Discovery is not merely a studio-and-streaming company. Perrette serves as president of WBD streaming and gaming as well as the business leader of HBO Max. The source material does not identify particular game studios, projects, platforms or franchises that would be covered by settlement commitments. It would be premature to claim that a settlement would dictate release plans, staffing levels or creative decisions within games.
Still, the merger debate is relevant to games for a practical reason: corporate ownership shapes which executive teams set budgets, prioritize platforms, approve projects and define longer-term strategy. A requirement to operate assets separately could preserve distinct operational boundaries for a time. Conversely, a combined ownership structure may still centralize ultimate authority even if internal labels, teams or reporting lines remain separate.
This is not a prediction of a particular gaming outcome. It is the corporate-governance implication of the remedy dispute: operational separation and ownership separation can produce very different levels of independence. The distinction is worth keeping in mind as deal language emerges, particularly because the available reporting says Perrette and HBO CEO Casey Bloys appear to be moving into deal-closing mode.
Readers following the business decisions that ripple through games can also see a related discussion of buyer trust and corporate timing in our look at Retroid’s Duo Lite+. The circumstances are plainly different, but transparency and the practical meaning of corporate commitments are recurring concerns across the industry.
Organized opposition is escalating
As negotiators work toward a possible resolution, the Block the Merger coalition has said the rumored settlement framework is unacceptable. Its objection is not simply to the timing of the deal; it is to the idea that promises about future conduct could substitute for more permanent changes to ownership.
Actor Mark Ruffalo has amplified that pressure campaign, calling on supporters to urge Bonta not to settle on what he characterized as empty promises. Ruffalo stars in the HBO drama Task, which has been renewed for a second season, placing his public anti-merger advocacy in an unusual position relative to one of the companies involved.
Ruffalo asked supporters to gather outside Bonta’s Oakland office at 5 p.m. Sunday. Further events were planned outside New York Attorney General Letitia James’ office on Monday and the Writers Guild of America West headquarters in Los Angeles on Tuesday.
The Writers Guild of America has filed a separate antitrust lawsuit alleging that the transaction would unlawfully shrink the market for writers’ work. The guild is party to the stipulation preventing the merger from being completed before a March 2027 federal trial, though it has not participated in the settlement talks between Paramount and the states.
The separate bond fight
The litigation is also generating a high-stakes fight over the cost of delaying the transaction. Paramount is seeking a $1.88 billion bond from the WGA and the states as the price of keeping the merger on hold. The case is set to appear before Judge Araceli Martinez-Olguin on Thursday.
A bond in this context is financial security sought by a party that says it could suffer losses if an injunction or similar restraint later proves unwarranted. Paramount’s request is separate from the question of whether the merger is anticompetitive, but it raises the financial stakes for the plaintiffs pressing the challenge.
The next development could arrive quickly if the state coalition and Paramount Skydance reach an agreement. Yet a settlement would not erase all conflict around the transaction. Opponents are already focused on the enforceability and substance of any conditions, while the WGA’s separate case and the existing restriction on closing remain important parts of the larger legal picture.
For now, the most important unknown is not whether the companies can describe their operations as separate. It is whether the states accept terms that create enforceable, meaningful independence—or decide that only different ownership can answer their antitrust concerns.