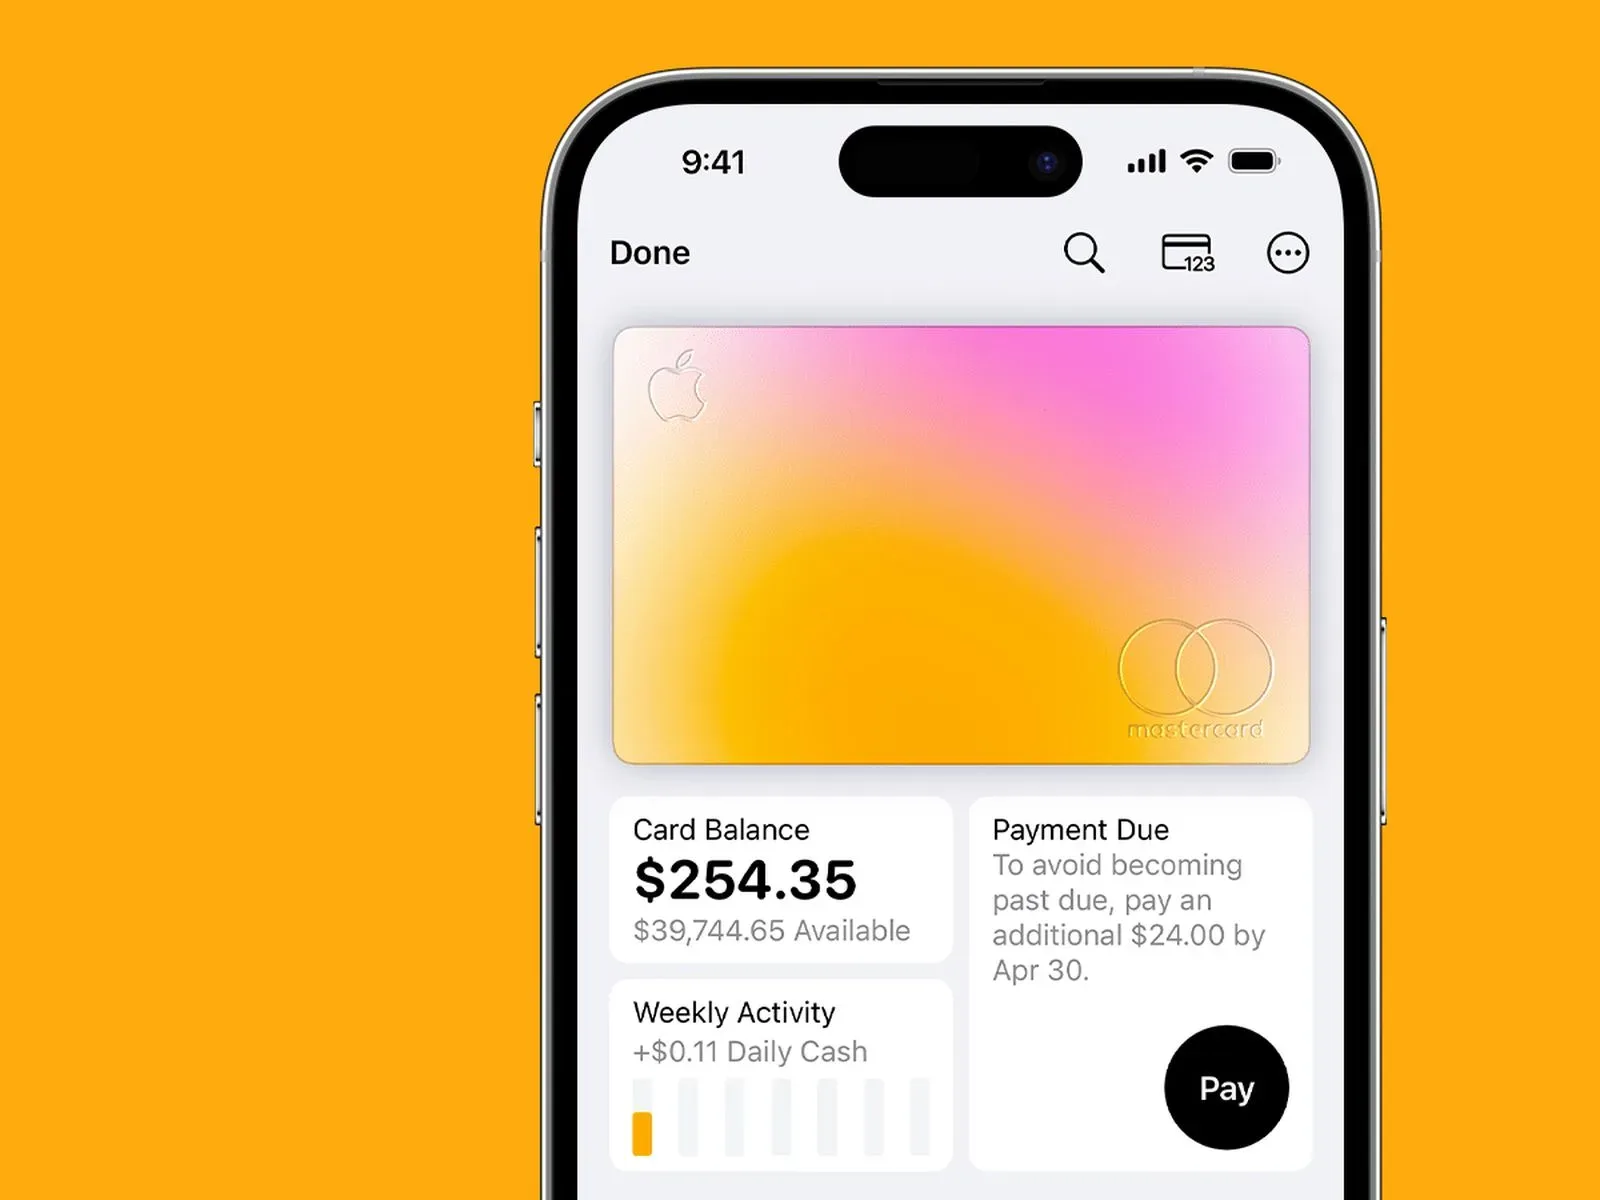
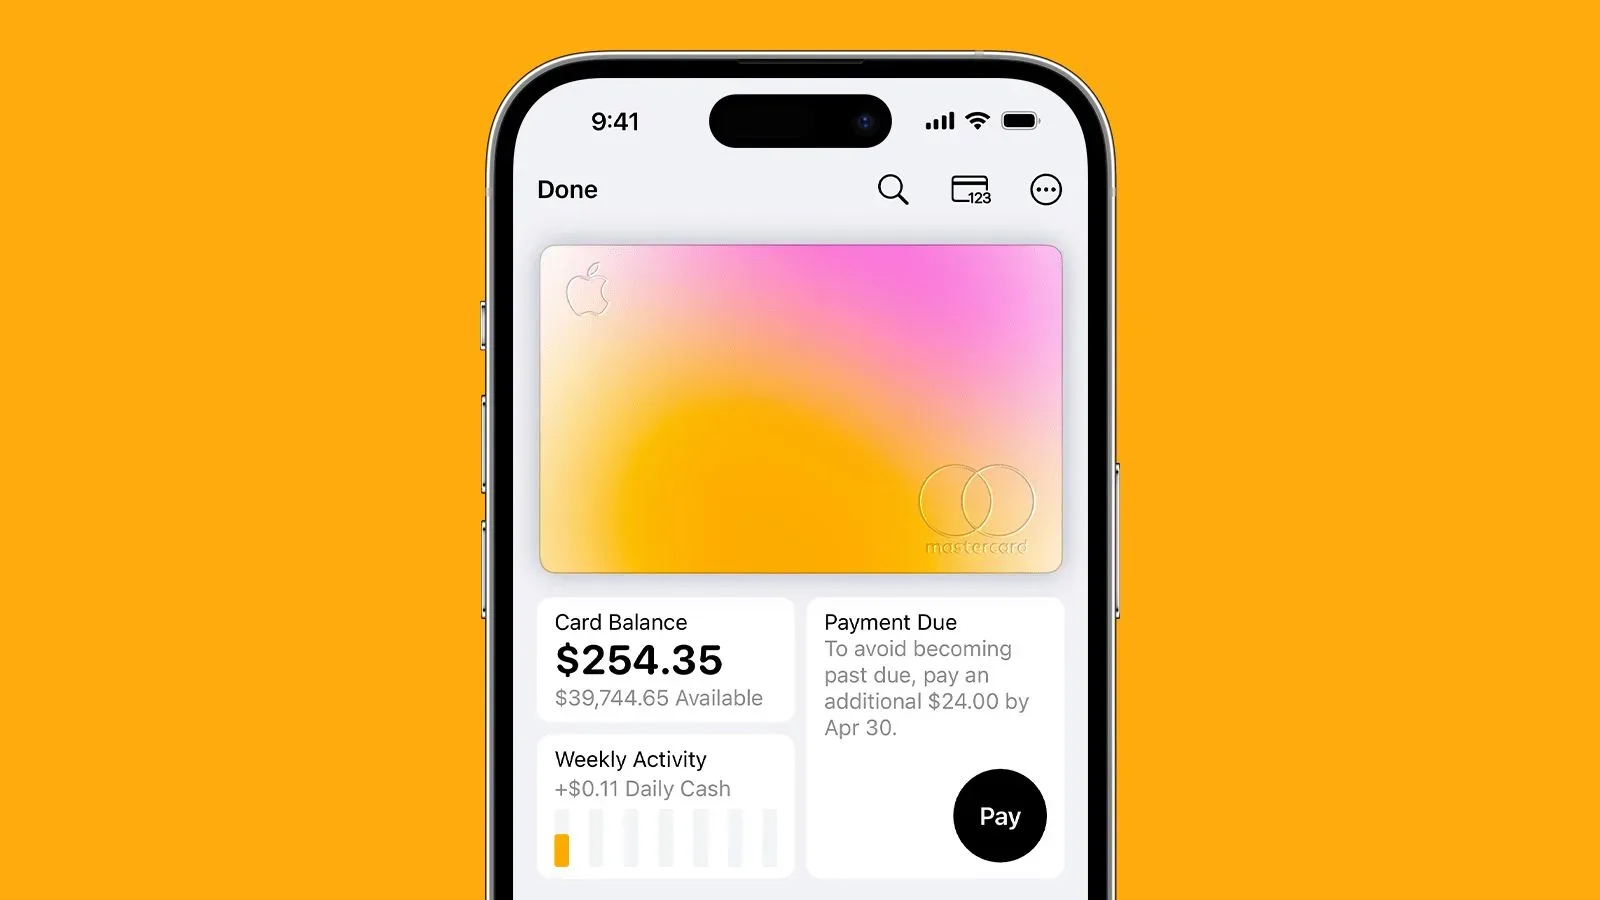
Apple is offering eligible new Apple Card applicants a limited-time promotion that doubles the card’s Daily Cash rewards for the first year after an account is opened. The offer is aimed at iPhone users who apply by December 10 through the designated promotion website, and it has a meaningful ceiling: the extra rewards are capped at $1,000 in bonus Daily Cash.
The headline number is 6% Daily Cash, but it applies only to purchases at Apple and participating merchants when Apple Pay is used. Other spending earns at different doubled rates. The structure matters, because the maximum advertised return is not a blanket 6% on every purchase and because the $1,000 cap refers to the promotional bonus, not total cash-back earnings.
What the doubled Daily Cash rates are
During the promotional period, qualifying purchases fall into three reward tiers:
- 6% Daily Cash: Apple and participating merchants when paying with Apple Card through Apple Pay.
- 4% Daily Cash: other purchases made with Apple Card through Apple Pay.
- 2% Daily Cash: purchases made with the physical Apple Card or a virtual card number without Apple Pay.
Daily Cash is Apple Card’s cash-back reward system. In this promotion, “double” means each normal rate is increased by an equivalent amount: the usual 3% category becomes 6%, the 2% Apple Pay rate becomes 4%, and the 1% rate for non-Apple Pay card use becomes 2%.
That distinction is important for anyone reading “up to 6%” as a general shopping rate. The 6% figure depends on both the merchant qualifying and the payment being made through Apple Pay. A purchase at a merchant outside the participating group, even if it is made with Apple Pay, is described by the promotion as earning 4%. Paying without Apple Pay lowers the promotional rate further to 2%.
The $1,000 figure is a cap on the extra reward
Apple’s stated maximum is often the part of a rewards offer that attracts attention, but the spending required to get there shows how the limit works in practice. Reaching the full $1,000 promotional bonus would require approximately:
- $33,333 of eligible spending at the 6% rate;
- $50,000 of eligible spending at the 4% rate; or
- $100,000 of eligible spending at the 2% rate.
Those amounts arise because only the additional rewards generated by the doubling count toward the bonus ceiling. At the 6% promotional tier, for example, the standard rate is 3%, so the extra promotional portion is 3 percentage points. Three percent of roughly $33,333 is about $1,000. The same logic produces the larger spending totals at the other rates: the incremental promotion is 2 percentage points on the 4% tier and 1 percentage point on the 2% tier.
This is a useful way to separate total Daily Cash from bonus Daily Cash. Spending $33,333 in the 6% category would produce close to $2,000 in Daily Cash overall during the promotion: roughly $1,000 at the ordinary 3% rate and roughly $1,000 from the temporary doubling. The offer’s cap applies to that second portion.
A year of elevated rewards, unless the cap arrives first
The doubled rates run for the first year after the account is opened, or until the $1,000 bonus limit is reached—whichever happens first. Once either threshold is met, the card reverts to its regular Daily Cash rates of 3%, 2%, and 1%, depending on the relevant payment method and merchant category.
For many cardholders, that means the time limit is likely to matter more than the dollar cap. The spending needed to reach the ceiling is substantial, particularly for people whose usual purchases do not fall into the 6% Apple-and-participating-merchants bucket. The value of the promotion will therefore depend less on its top-line maximum than on a person’s normal use of Apple Pay and where they already shop.
It also makes payment method unusually consequential. Within the offer’s terms, using Apple Pay on an ordinary qualifying purchase earns 4%, while using the physical card or virtual card number without Apple Pay earns 2%. In plain terms, the payment route can double the reward rate for a purchase outside the special 6% merchant group.
Eligibility and application route are central
The offer is not available to current Apple Card holders, and it also excludes people who have previously had an Apple Card. It is specifically for new users. Apple says applicants need to use the promotion website, noting that the deal may not appear through other application paths.
That last point is practical rather than cosmetic. A prospective applicant who wants the promotional terms should verify that they are applying through the designated route before submitting an application. The offer is also limited to the United States, consistent with Apple Card’s U.S.-only availability.
How to read the offer without overestimating it
The promotion is straightforward as a rewards multiplier, but it has several boundaries worth keeping separate:
- “Up to” describes the best available tier. Six percent is tied to Apple and participating merchants paid via Apple Pay, not all transactions.
- The year starts after account opening. The eligibility deadline is December 10, while the elevated-reward period is measured from when the account is opened.
- The $1,000 limit is not an automatic payout. It is the highest possible amount of extra Daily Cash, requiring enough eligible spending to generate it.
- Apple Pay affects the rate. The offer gives 4% for Apple Pay purchases outside the 6% tier and 2% for physical-card or virtual-number purchases without Apple Pay.
- Existing and former cardholders are excluded. Having had an Apple Card before is enough to put someone outside the promotion.
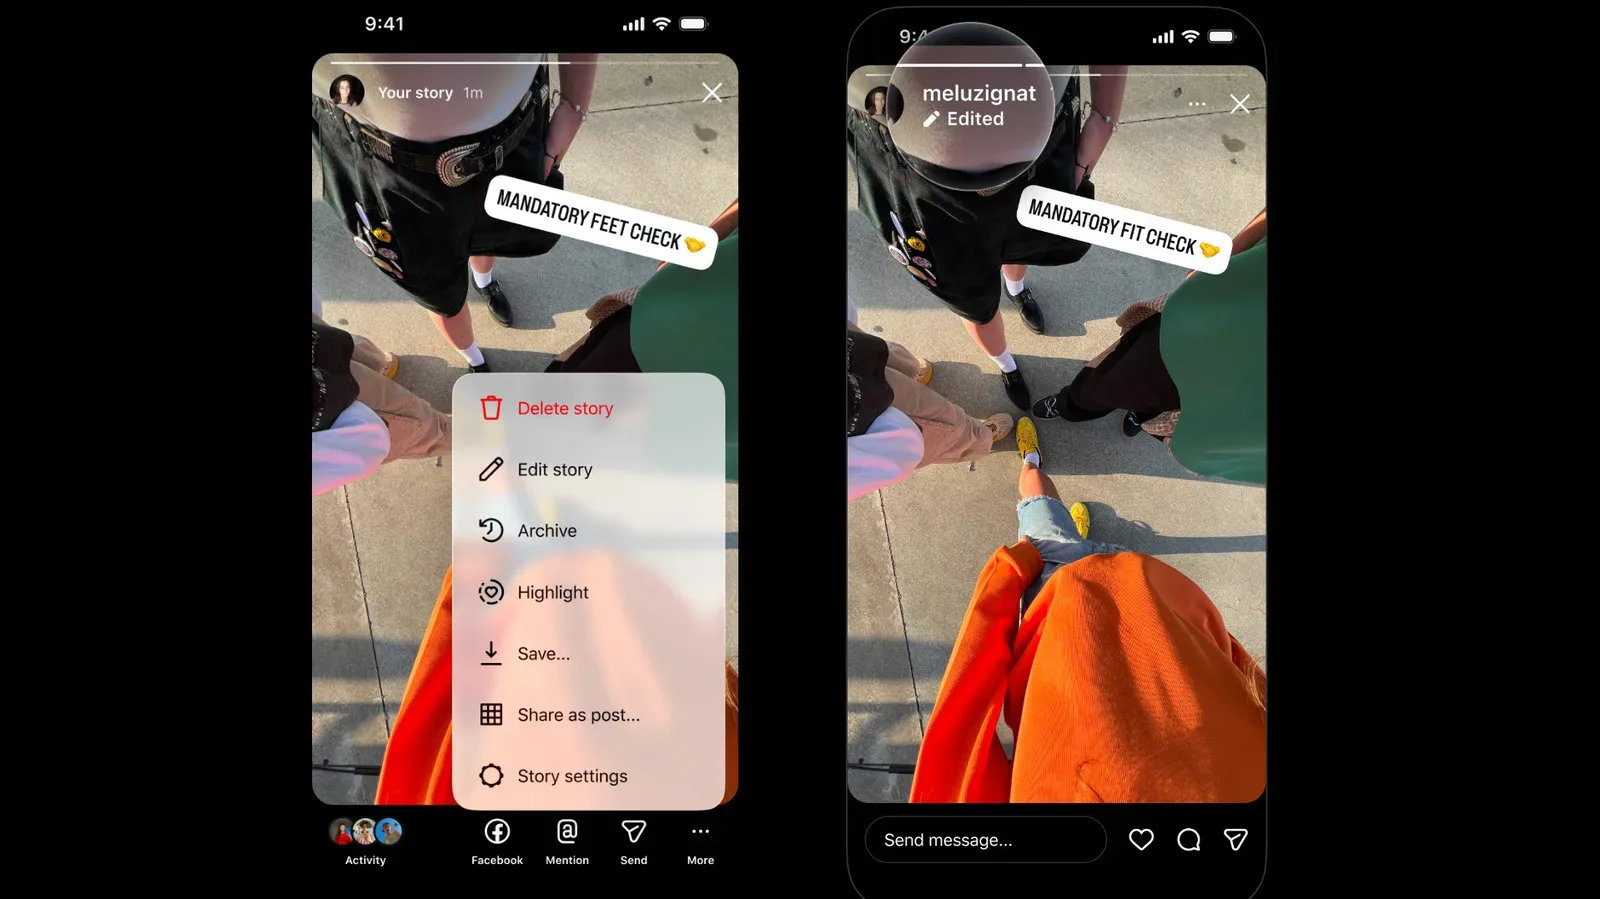
There is a broader mobile-commerce angle here as well. The offer gives its strongest ordinary-purchase rate to Apple Pay transactions, rewarding use of the phone-based payment method rather than only use of the underlying credit card. That emphasis fits a wider push by consumer technology companies to make their devices and services more central to everyday purchases. For another example of how platform companies are continuously refining consumer-facing digital features, see this report on post-publication editing for Instagram Stories.
What the promotion means for different spending patterns
Someone who already makes frequent Apple Pay purchases may see a clear, easily understood lift: the ordinary 2% rate becomes 4% for the promotional period. For purchases made at Apple or the participating merchants, the reward can climb to 6%, though shoppers should not assume a merchant participates without confirming that it is included.
Conversely, a person who commonly types in a virtual card number, uses the physical titanium card, or shops in situations where Apple Pay is not used will receive the lower 2% promotional rate. That is still double the card’s standard 1% for those purchases, but it is much different from the offer’s headline rate.
The cap also discourages treating the offer as an invitation to spend solely for rewards. At each tier, rewards remain a percentage of money spent. The offer can increase the return on planned, qualifying purchases, but its maximum requires tens of thousands of dollars in spending. The clearest interpretation is that it is a temporary benefit for eligible new users whose existing purchase habits already align with Apple Pay and the participating merchant categories.
Apple has positioned the campaign around a holiday sign-up window, but its more durable effect is to give qualified newcomers a year in which payment choice has a larger-than-normal impact on Daily Cash. Applicants considering it should focus on the qualification deadline, the designated application website, their new-user status, and the difference between the 6%, 4%, and 2% paths rather than the $1,000 maximum alone.