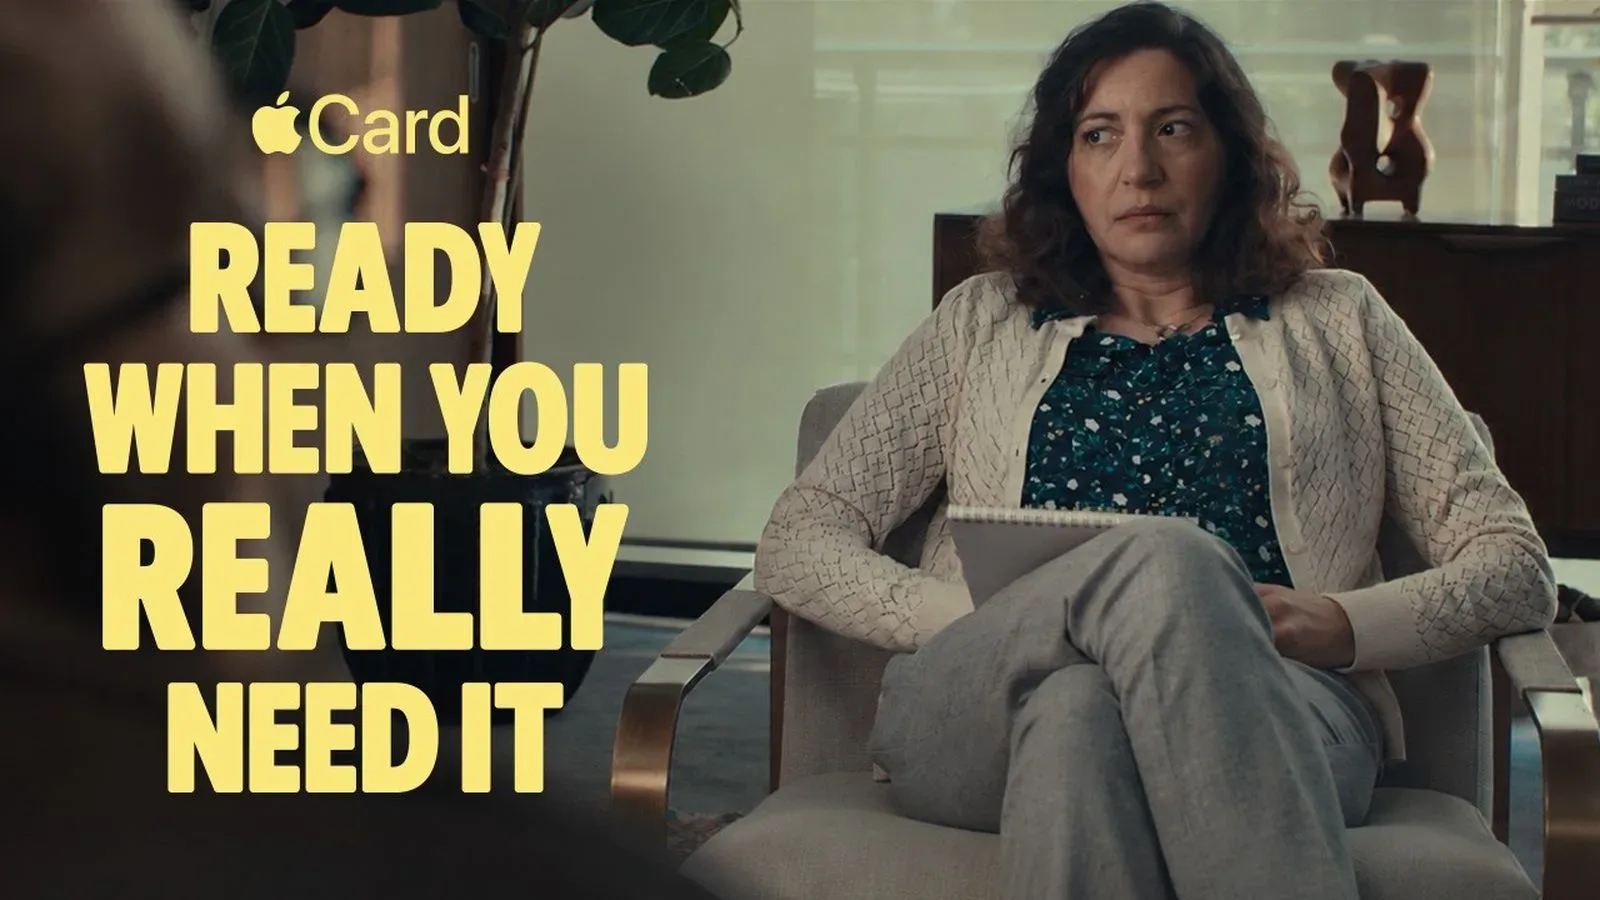
Apple’s newest Apple Card advertisement has a very clear pitch: the traditional wait for a piece of plastic is not invited to this party.
The campaign frames the card as something an eligible iPhone owner can apply for in as little as a minute, then use shortly after approval. In Apple’s telling, it is a few taps, an answer, and a payment method ready for action—less “wait for the mail carrier” and more “the checkout screen is already looking at you.” The ad also highlights unlimited Daily Cash.
That message fits the product’s core setup. Apple Card is built into the iPhone rather than being introduced primarily as a physical card in a wallet. Its immediate-use angle is therefore not merely about speed for speed’s sake: it is about a card that can exist in a digital purchasing flow before a physical counterpart would arrive.
But the smooth commercial version of any credit application deserves one large, non-skippable tooltip. Apple Card remains a credit product, available only to U.S. iPhone owners, and the application process has credit-report implications. A soft credit check is used when someone applies; accepting an offer results in a hard credit inquiry.
A fast application is not the same thing as automatic approval
The ad’s language centers on the possibility of applying quickly, getting approved and making purchases with little delay. Those are related steps, but they are not identical promises for every person who opens the application.
A soft credit check is an inquiry used to assess an application without becoming the type of inquiry that is generally treated as a hard application for new credit. Apple says an Apple Card application requires this initial soft check. That matters because it gives a potential applicant a chance to receive an outcome before deciding whether to move forward with the offer.
A hard credit inquiry, by contrast, occurs once the applicant accepts the Apple Card offer. The distinction is particularly useful in a promotional message about convenience: there is a decision point between submitting an application for consideration and accepting the offered account.
Apple also provides information on its site about why applications can be approved or denied. The new advertisement does not turn approval into a certainty, and prospective users should not read “in as little as a minute” as a guarantee that every application will be approved in that amount of time—or at all. It describes the speed Apple says is possible for applying, not a universal outcome.
The physical-card waiting room is the target
The commercial’s most recognizable villain is not another financial product. It is the old delay: approval first, delivery later, and only then the ability to use a newly opened account in ordinary shopping.
Apple’s pitch is that this sequence can be compressed because the card is integrated into iPhone. Once approved and ready to use, a customer does not need to wait for a physical card to begin making purchases. That is a meaningful practical difference for people applying because they want access to a payment method promptly, though it should not be confused with a reason to apply without considering the account itself.
The company’s broader point is reinforced by common iPhone payment tools. AutoFill can supply credit-card information for online purchases, reducing the occasions when someone would need to read a number from a physical card. Many websites also accept Apple Pay, which can likewise make a physical card unnecessary for a web checkout.
In other words, Apple is selling an experience in which the payment credential is where a user already is: on the phone, in the browser, and at a compatible checkout. The plastic card is no longer the opening act. For this particular sales pitch, it is closer to bonus hardware.
What “built into iPhone” means for shoppers
“Built into iPhone” is the operative phrase in the ad, and it carries a few practical implications that are worth separating from the commercial’s speed-run energy.
- Eligibility is device-bound: Apple Card is limited to iPhone owners in the United States. Someone outside the U.S., or someone without an iPhone, is outside the stated audience for the product.
- Digital use comes first: The offer emphasizes making purchases without waiting for a physical card, supported by online AutoFill and Apple Pay acceptance on many sites.
- Approval still governs access: A quick application interface does not remove the approval step. The account can be used right away only after approval and acceptance.
- Daily Cash is part of the pitch: Apple says cardholders can earn unlimited Daily Cash and use it right away. The ad positions that immediacy as another benefit alongside immediate purchasing access.
There is a broader consumer-tech pattern here. Hardware and software companies increasingly want a transaction to feel less like a separate banking errand and more like another native phone function. The same instinct sits behind online payment autofill and tap-to-pay systems: remove as many handoffs as possible between deciding to buy something and completing the purchase.
That does not mean the financial decision itself should be treated as frictionless. In fact, the easier the application path becomes, the more useful it is for users to pause at the points that still require judgment: whether the offer is right for them, whether they understand the hard inquiry that follows acceptance, and whether a credit account suits their spending plans.
Why the credit-check detail belongs beside the convenience claim
Apple’s ad is doing what ads do: concentrating on the attractive part of the process. The appeal is straightforward. There is no quoted physical-card delivery wait, no fumbling through a drawer to find account details for an online order, and no implication that a user must postpone shopping until a card arrives.
Yet the application’s credit-check sequence is not minor fine print from the consumer’s perspective. It is part of the practical meaning of “apply in minutes.” An applicant can initiate the process through the iPhone with a soft inquiry involved, then faces the consequential decision of accepting an offer that triggers a hard inquiry.
That makes the product flow more nuanced than a one-button power-up. The convenience is real in the sense Apple describes—an approved card can be used without waiting for physical delivery—but it is convenience after an applicant has been evaluated and then chooses to accept an offered account.
For people who routinely buy games, add-ons, subscriptions or hardware online, the digital-payment story will sound familiar. Autofill and Apple Pay reduce the need to handle physical card details when a merchant supports them. That can make checkout feel notably smoother, whether the purchase is mundane or the kind of limited-stock item that turns a refresh button into an endurance sport. It does not, however, change the usual need to stay aware of spending.
Consumer technology often celebrates eliminated friction as though every speed bump were an enemy. In credit, some friction can be useful information. The soft-check/hard-inquiry boundary is one of those moments. It tells applicants that browsing the possibility of an offer and formally taking the account are different actions.
Daily Cash joins the immediate-use message
Apple also uses the ad to spotlight unlimited Daily Cash, saying it can be earned and used right away. In the context of the campaign, that statement extends the no-wait theme beyond the card itself. The idea is not just that the payment method appears quickly; the reward element is also presented as immediately usable.
The available details here do not lay out reward rates, eligible purchase categories, terms or other conditions, so those should not be assumed from the ad’s broad claim. What is clear is the positioning: Apple wants Daily Cash to read as a direct, active benefit rather than a reward that sits behind a later redemption process.
That framing is consistent with a product designed around the iPhone. The company is emphasizing a loop contained inside the device: apply, receive a decision, accept if desired, pay digitally, earn Daily Cash, and use it. The commercial turns that loop into a compact story because compact stories are better at selling than forms with several pages of decisions.
The practical takeaway for eligible iPhone owners
Apple’s new spot is a concise reminder of what differentiates Apple Card’s setup: it is designed to be applied for and used from an iPhone, with no required wait for a physical card before making purchases. Online AutoFill and Apple Pay at supported sites strengthen that proposition.
Still, the important qualifiers are straightforward. Apple Card is for U.S. iPhone owners. Applying involves a soft credit check. Accepting an offer involves a hard credit inquiry. And approval is an assessment outcome, not an entitlement unlocked by tapping quickly enough.
For consumers, that is the healthier way to read the advertisement. The iPhone can make the mechanics feel immediate; it cannot make the decision consequence-free. The card may be ready for checkout in a hurry, but applicants should give the choice more thought than they give a “continue” button when a game tutorial is trying to teach them how to jump.
Apple’s latest creative work therefore lands on a simple, credible product distinction: digital-first access can spare customers a physical-card delay. The less cinematic part is equally important: fast access starts with an application, and accepting the approved offer carries the hard-inquiry step Apple identifies. Convenience is the headline. Informed acceptance is the loading screen nobody should skip.
For another look at how consumer devices increasingly make everyday technology more self-contained, see this report on Eufy’s Window Camera E10.