Prime Video has reached a meaningful financial milestone inside Amazon’s sprawling business: CEO Andy Jassy says the streaming operation is now profitable in its own right.
On the company’s third-quarter earnings call, Jassy described Prime Video as a business with a revenue run rate in the tens of billions of dollars. That wording matters. It is Amazon’s clearest indication in this update that video is being framed not simply as a membership perk or a long-term strategic expense, but as a sizable operation that can stand on its own financially.
The claim arrived during a rougher market moment for Amazon. Its share price fell after the company missed third-quarter earnings expectations, advertising revenue growth slowed, and heavy AI-infrastructure investment weighed on free cash flow. Against that backdrop, Prime Video was presented as one of the areas where Amazon sees momentum.
For viewers, the immediate takeaway is not a newly announced feature, price, or programming change. It is a window into why Prime Video’s mix of scripted series, movies and live sports remains so central to Amazon’s broader entertainment strategy—and why expensive content commitments are likely to be judged against measurable reach as well as cultural buzz.
What “profitable in its own right” means—and what it does not
Amazon did not provide a standalone profit figure for Prime Video in the information disclosed here. So the statement should not be read as a detailed breakdown of the service’s revenue, costs or margin. “Profitable in its own right” is a high-level assessment from the company’s CEO, rather than a separate set of segment accounts.
Likewise, a revenue run rate is not the same thing as revenue reported for a completed year. It is a way of describing the scale implied by the current pace of business, generally by annualizing recent performance. Jassy’s “tens of billions” description signals considerable size, but Amazon has not specified what portion comes from subscriptions, advertising, rentals, add-on channels, licensing, or other video-related activity in the supplied figures.
That distinction is useful because streaming economics are rarely captured by a single audience number. A hit can attract viewers, strengthen the perceived value of a membership, bring advertisers to the platform, and give the service programming it can promote over a longer period. The information here establishes Prime Video’s claimed profitability, but it does not disclose how much each of those inputs contributes.
It also does not mean content is suddenly inexpensive. Amazon’s third-quarter filing lists total video and music expense of $5.9 billion for the period, about 7% above the comparable period a year earlier. Across the first nine months of 2026, content spending was $18.8 billion, up roughly 20% year over year.
Those figures combine video and music, so they cannot be used to calculate a Prime Video-only cost. They do, however, show the scale of the wider entertainment spend occurring alongside Amazon’s profitability assertion. The key point is not that investment has slowed; the reported numbers instead show a larger overall content outlay.
Sports are supplying a major audience engine
Live sports are a prominent part of Jassy’s case for Prime Video’s current momentum. He cited Thursday Night Football, NBA on Prime, NASCAR, the Masters and UEFA Champions League soccer among the service’s live offerings.
Thursday Night Football has had its best start ever in 2026, Amazon said. Through six games in the fifth season of the package on Prime Video, the broadcasts averaged 17.7 million viewers, based on Nielsen data. That is a 16% increase over the prior season’s full-season average.
The second season of NBA on Prime also opened strongly. Its season-opening doubleheader drew more than 2 million U.S. viewers, Amazon said, citing Nielsen. The company characterized that as more than twice the previous year’s full-season average.
Live rights matter because the programming is time-sensitive. A viewer can catch up on a drama later, but a game’s main appeal is the shared moment of watching it unfold. For a streaming service, that creates recurring appointment viewing and frequent promotional opportunities around each event. It can also make the service attractive to advertisers seeking large audiences at a defined time.
Still, the two reported sports metrics are not directly interchangeable. The football number is an average through six games, while the basketball number concerns an opening-night doubleheader. They indicate encouraging starts for their respective properties, but they are measuring different events and time frames. Reading them responsibly means treating each as evidence of audience scale, not as a simple ranking of one sport against another.
Scripted series remain a second pillar
Prime Video’s argument is not built on sport alone. Jassy pointed to Carrie, The Summer I Turned Pretty, The Boys, Off Campus, Reacher and Fallout as shows with momentum. He also named Amazon MGM Studios film Project Hail Mary as a breakout movie.
Of those titles, Amazon supplied specific performance figures for Reacher and Carrie. Season 4 of Reacher reached 66 million viewers globally in its first 28 days, the company said. That is a substantial worldwide figure, though Amazon has not detailed the methodology behind the viewer count in the information provided.
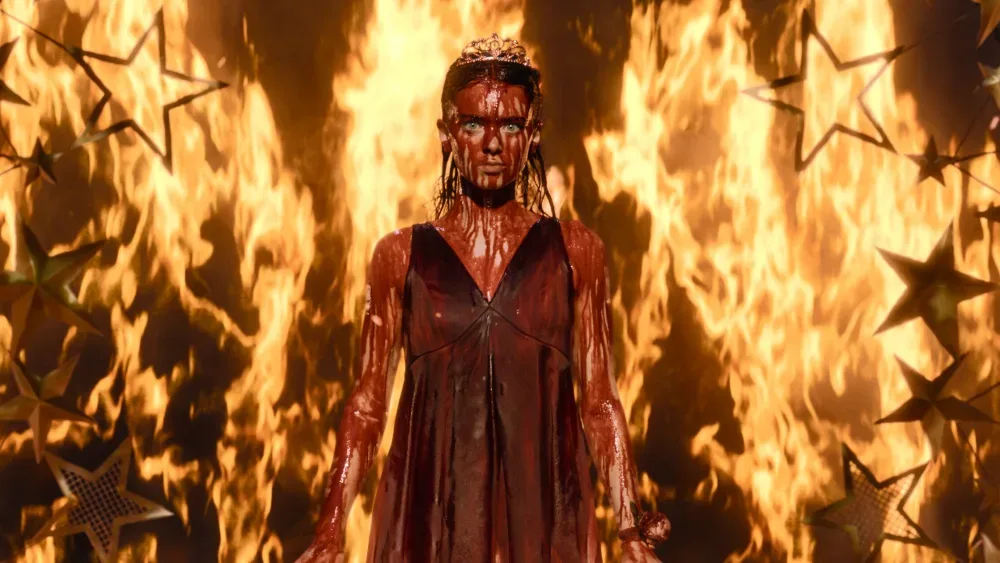
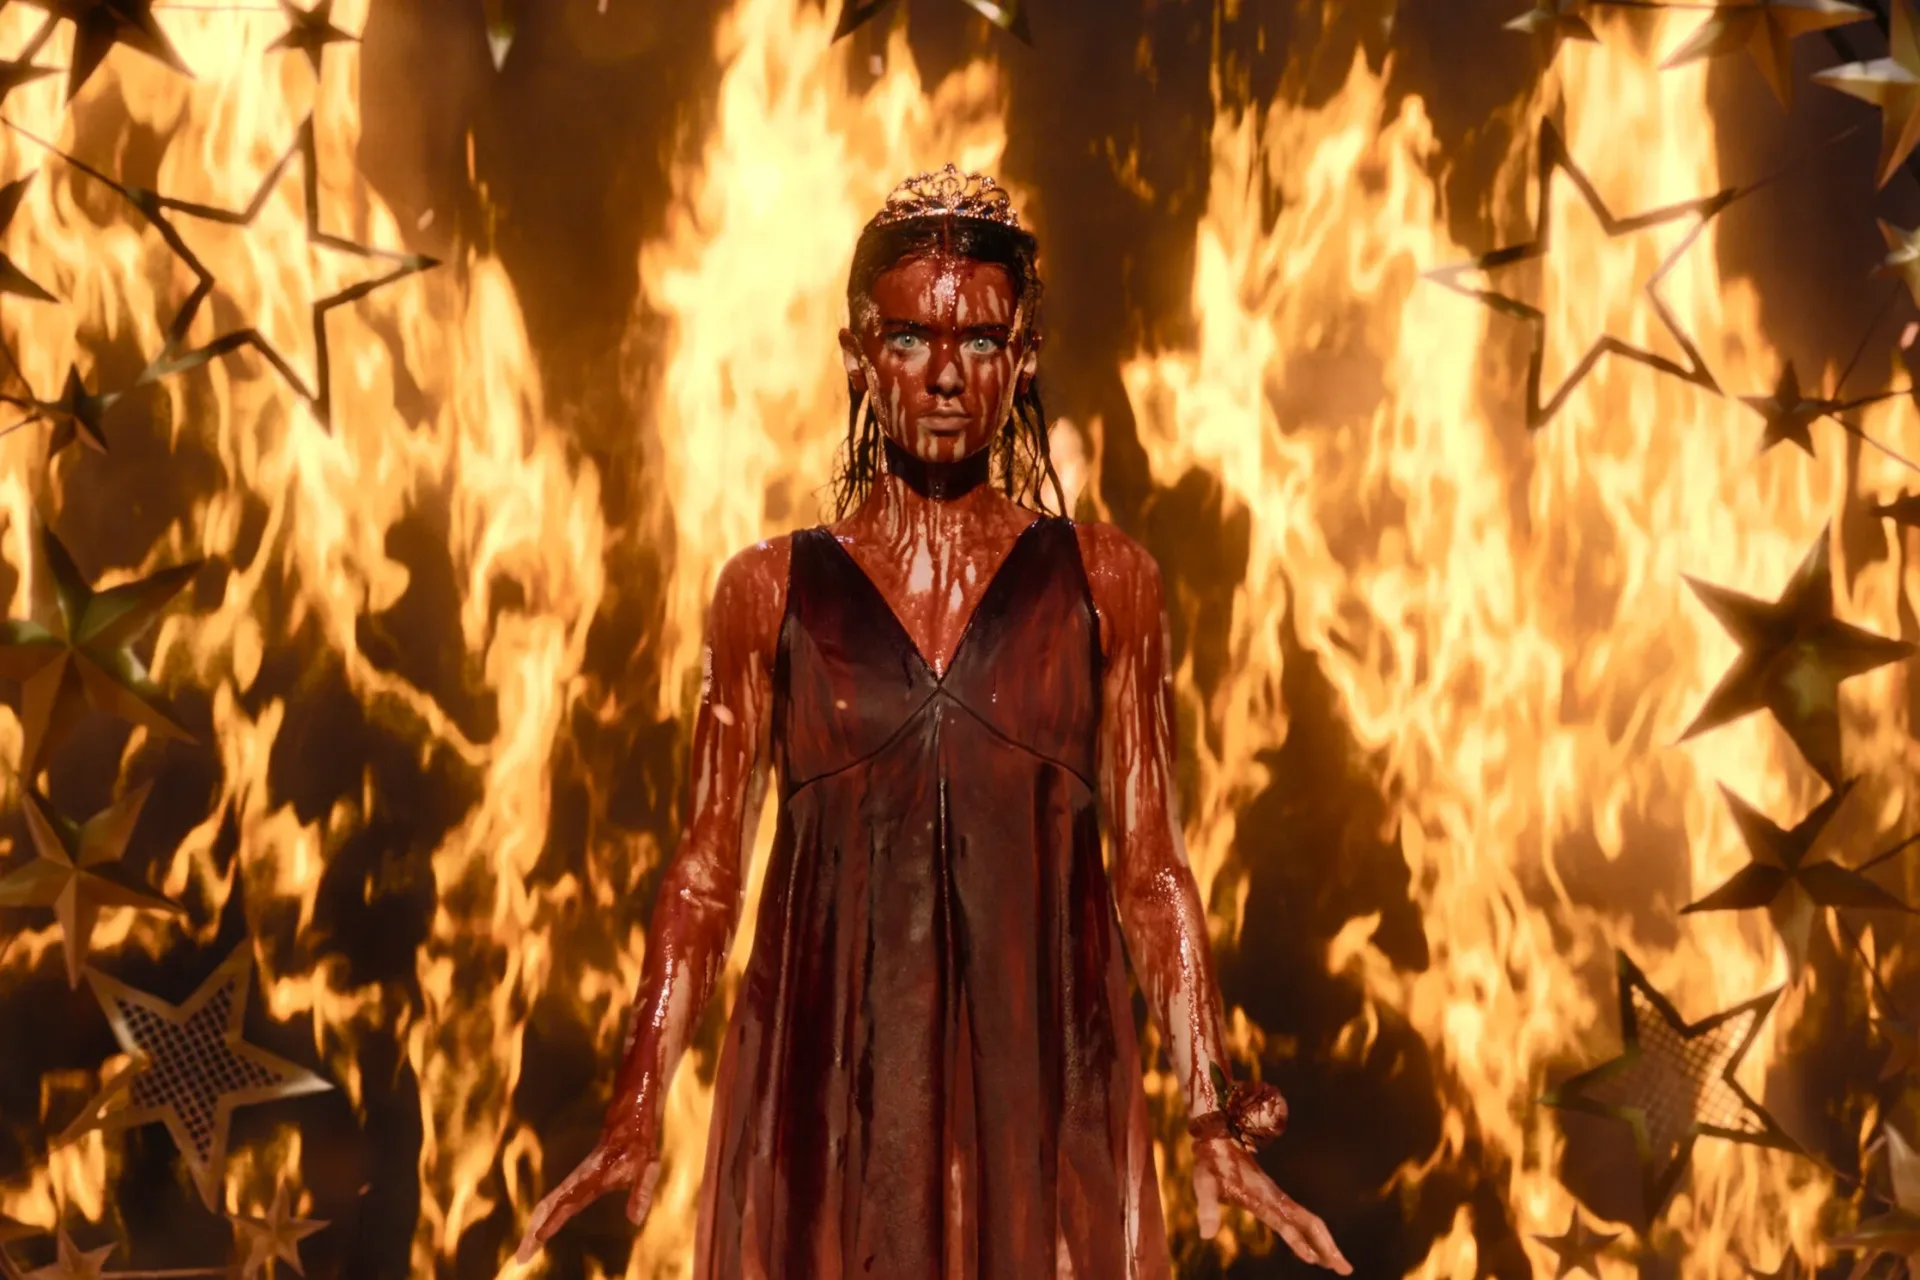
Carrie, starring Summer H. Howell as Carrie White, premiered October 7. Through October 22, it had generated more than 2.1 billion minutes viewed, based on Luminate data. Minutes viewed measures total time spent watching rather than counting individual people. It can therefore reflect both a large number of viewers and deeper viewing per person; by itself, it does not reveal precisely how many accounts or individuals watched.
That measurement difference is especially important in streaming coverage. A title reported in viewers and a title reported in minutes viewed cannot be converted into a clean head-to-head comparison without additional data such as runtime, episode count and the platform’s definition of a viewer. Both figures show demand, but they describe it from different angles.
For audiences, the practical implication is a broadening programming proposition. Sports can create weekly or event-based urgency, while returning series and new shows keep the catalog active between broadcasts. Movies add another release cadence. Amazon’s leadership is presenting the combination—not one individual show or league—as the foundation of Prime Video’s business case.
Why the spending figures change the interpretation
The $18.8 billion video-and-music expense total for the first nine months is a reminder that profitability does not eliminate pressure to prove value. Content is a continuing commitment: new seasons need to work, live sports need to hold an audience, and movies need to break through a crowded streaming field. Rising spending raises the stakes for every part of that slate.
Amazon’s earnings update offers several signs that its current programming is finding viewers, particularly in live sports and with established scripted franchises. But it does not establish a formula for every title. A business can be profitable overall while individual projects deliver very different results. No title-by-title costs, revenues, completion rates or retention data were included in the figures supplied here.
That gap is why the reported metrics are most useful as indicators of momentum rather than a final scorecard. Thursday Night Football’s audience improvement shows growth against the previous season’s average. The NBA doubleheader points to an opening-night lift. Reacher and Carrie show that scripted programming is contributing attention at scale through two different measurement systems.
The broader Amazon context
The Prime Video update arrives while Amazon is balancing several expensive priorities. Investor concern over major AI infrastructure spending and its effect on free cash flow provided the larger context for the quarter. Free cash flow is the cash a business has left after paying operating costs and capital expenditures; it is often watched because it shows how much financial flexibility remains after investment needs are met.
That does not make video and AI spending the same thing, nor does the available information quantify a direct relationship between them. But it does explain why management highlighted a profitable entertainment operation in the same discussion as wider investment pressures. A business unit described as both large and profitable is a valuable counterpoint when the market is focused on near-term costs elsewhere.
Amazon’s ambitions around technology investment have also become a major industry conversation; the continuing AI copyright debate is one example of the broader questions surrounding how major digital platforms build and use new systems. In this earnings update, however, the concrete entertainment story is simpler: Amazon says its streaming business is profitable while it continues to spend heavily on video and music programming.
Prime Video’s next test will be sustaining that position. The current results point to a service with high-profile live events, returning series with global reach, a new show accumulating billions of viewing minutes, and a movie pipeline Amazon characterizes as producing breakouts. Whether that combination keeps delivering at the same level will depend on future audience behavior and costs—figures not yet disclosed. For now, Amazon is making its strongest case that Prime Video has moved beyond being merely an attractive extra inside Prime and into a profitable entertainment business of considerable scale.