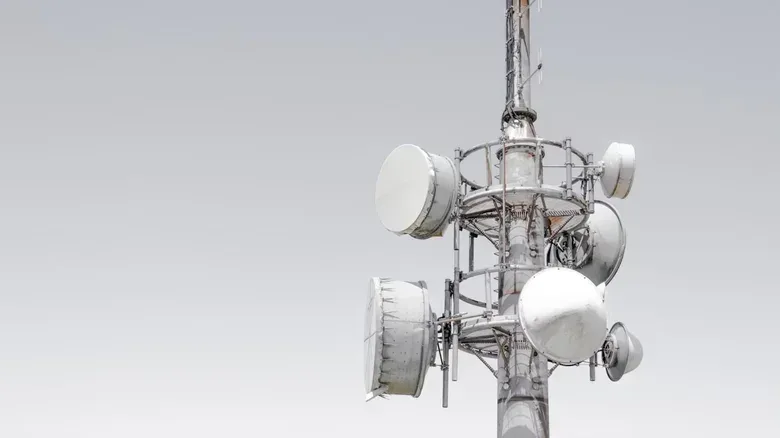
AT&T, T-Mobile and Verizon are taking the unusual step of working together on satellite connectivity, forming an unnamed joint venture intended to reduce the parts of the United States that have little or no mobile service. The plan is not presented as a replacement for conventional cellular infrastructure. Instead, satellites would complement the carriers’ existing ground-based networks in areas where normal coverage is limited.
That distinction matters. A mobile dead zone is simply a place where a phone cannot maintain usable service through the traditional network of terrestrial equipment. The new venture’s stated objective is to make those gaps much less common, with the companies saying it could nearly eliminate US dead zones currently without mobile service. No timetable has been given for when customers might receive connectivity through the arrangement, so the announcement is a statement of direction rather than a launch notice.
What the three-carrier venture is trying to do
The three companies had previously said they would pool resources to expand satellite coverage. The newly described structure gives that effort a formal operating vehicle: it will have a board containing representatives from all three carriers, plus an interim chief executive, Paul Roth, who brings industry experience to the role.
Satellite connectivity is the central technical piece. Rather than relying entirely on nearby towers and other ground-based network equipment, a satellite-enabled service can potentially reach places where that equipment is absent or unavailable. The companies describe this as an extension of existing mobile networks, not a wholesale shift away from them.
That framing is important for expectations. Nothing in the information released establishes a universal service date, identifies compatible phones, spells out which satellite technology will be used, or details what a connection will support. It also does not say whether the first functions will be messaging, calling, data, emergency tools, or some combination. “Satellite coverage” can sound like a single finished feature, but the announcement currently provides a mission and management structure, not a consumer feature list.
Emergency access is one of the clearest stated goals
The carriers have highlighted reliable connectivity during emergencies, particularly when usual terrestrial networks are unavailable. That could be significant in situations where normal infrastructure is disrupted or where users are outside regular coverage in the first place. A connection that exists only when it is needed most can be materially different from ordinary day-to-day service.
Still, the practical value will depend on implementation details that have not been shared. Reliability in an emergency is a stated aim, not a demonstrated outcome at this early stage. Consumers should avoid treating the venture itself as proof that every location will soon have equal signal quality or that satellite access will work identically to a normal connection.
The companies also say customers could see better network performance through simpler access to satellite services across providers. In theory, a jointly built framework may reduce friction between carrier systems, help feature updates move faster, and lower the chance of a connection dropping when satellite access becomes relevant. Those are potential operational benefits of shared work, but the public information does not yet explain how access, handoffs, plans, or device support would work in practice.
Why cooperation is notable
AT&T, T-Mobile and Verizon are direct competitors for wireless customers. A shared satellite-focused venture therefore stands out: they are cooperating on a coverage problem while continuing to compete for subscribers through their normal services.
There is a straightforward strategic reason for that arrangement. Dedicated satellite-mobile providers are emerging as possible competitors, including Starlink and Amazon’s Leo. Building a joint effort could let the established mobile carriers address satellite-enabled coverage without each creating entirely separate solutions. It may also give them a common route for integrating satellite services with the networks and customer relationships they already operate.
That is analysis of the competitive picture, rather than a claimed explanation from the companies. The available details do not assign a specific business motive to any participant. But the timing and focus make the defensive logic easy to see: if satellite connectivity becomes a meaningful part of mobile service, the largest conventional carriers have reason to make sure they remain involved in the experience.
What “complementing” a mobile network means
A conventional mobile network depends on physical infrastructure spread across a service area. Coverage can be limited where that infrastructure is sparse, difficult to deploy, damaged, or otherwise unavailable. Satellite service is being positioned here as an additional path rather than the foundation of the entire network.
For customers, “complement” should not be read as “replace.” The announcement does not promise that satellite links will deliver the same experience as normal mobile coverage, or that every existing device and plan will immediately gain a new layer of service. It means the partners want another option for places where the usual network cannot adequately reach.
For players and other people who depend on connected devices, the practical implication is more about continuity than an announced upgrade to high-bandwidth use. A satellite backstop could eventually matter when a user is away from ordinary coverage or when terrestrial service is interrupted. But there is no basis in the disclosed information to assume improved online-game performance, faster downloads, or any particular gaming-specific benefit. Those outcomes would require capabilities the venture has not described.
Gaming hardware is increasingly connected in its own right, whether through consoles, handhelds, controllers, companion apps, or online services. That wider hardware landscape is visible in products such as Nacon’s Revolution 5 Unlimited for PS5, but this carrier initiative remains a separate, early-stage network project. The relevant point is not that the venture has announced a gaming feature; it has not. It is that connectivity infrastructure increasingly sits behind a broader range of entertainment devices and services.
Questions still unanswered
The announcement leaves several major consumer questions open:
- Availability: There is no disclosed start date for connectivity in US dead zones.
- Coverage: The stated goal is to nearly eliminate areas currently without mobile service, but no map or specific rollout regions have been provided.
- Devices and plans: The venture has not detailed which handsets or customer plans will work with the service.
- Supported uses: There is no public breakdown of what users will be able to do over the satellite connection.
- Provider experience: The companies promise simpler cross-provider access, but have not explained the customer-facing process.
Those omissions are normal for an initiative that still appears to be in its early stages, but they are also the details that will determine whether the venture changes everyday mobile service. The headline promise is ambitious; the next meaningful milestones will be technical specifics, rollout information, and a clear explanation of what customers can actually use.
What to watch next
For now, the concrete developments are the creation of the joint venture, its three-carrier governance, Paul Roth’s interim CEO role, and the plan to use satellites alongside established networks. The companies are aiming at a recognizable problem: locations where regular mobile coverage is not available and emergencies that can undermine ground-based connectivity.
The venture’s success should ultimately be measured against the claims it has made. Can it meaningfully reduce dead zones? Can it provide dependable access when conventional networks are unavailable? And can it make satellite features easier to access across the three providers without creating a confusing new layer for customers? Those questions remain open until the partners disclose a rollout and demonstrate the service in operation.
Until then, this is a notable alignment among the biggest US mobile carriers and a clear sign that satellite connectivity is becoming part of their long-term planning. It is not yet a reason to expect an immediate change in a phone’s signal, but it may shape how all three approach coverage gaps in the years ahead.