Meta’s third-quarter results present two sharply different pictures of the company at once: a fast-growing core business and an unusually large legal bill that reshaped the quarter’s reported profit. Revenue reached $64.6 billion, while the company reported $3.83 in earnings per share, below the $5.46 expected by analysts polled by LSEG Data & Analytics. Yet Meta shares rose 5% after the market closed, suggesting investors focused more on revenue growth and the non-recurring nature of the settlement-related hit than on the headline earnings miss.
The central number is a $9.89 billion cost connected to Meta’s $18 billion nationwide settlement with 52 state attorneys general. That charge helped push third-quarter costs to $51.6 billion. Meta said operating income would have been $22.88 billion without the settlement cost, rather than the reported $12.98 billion.
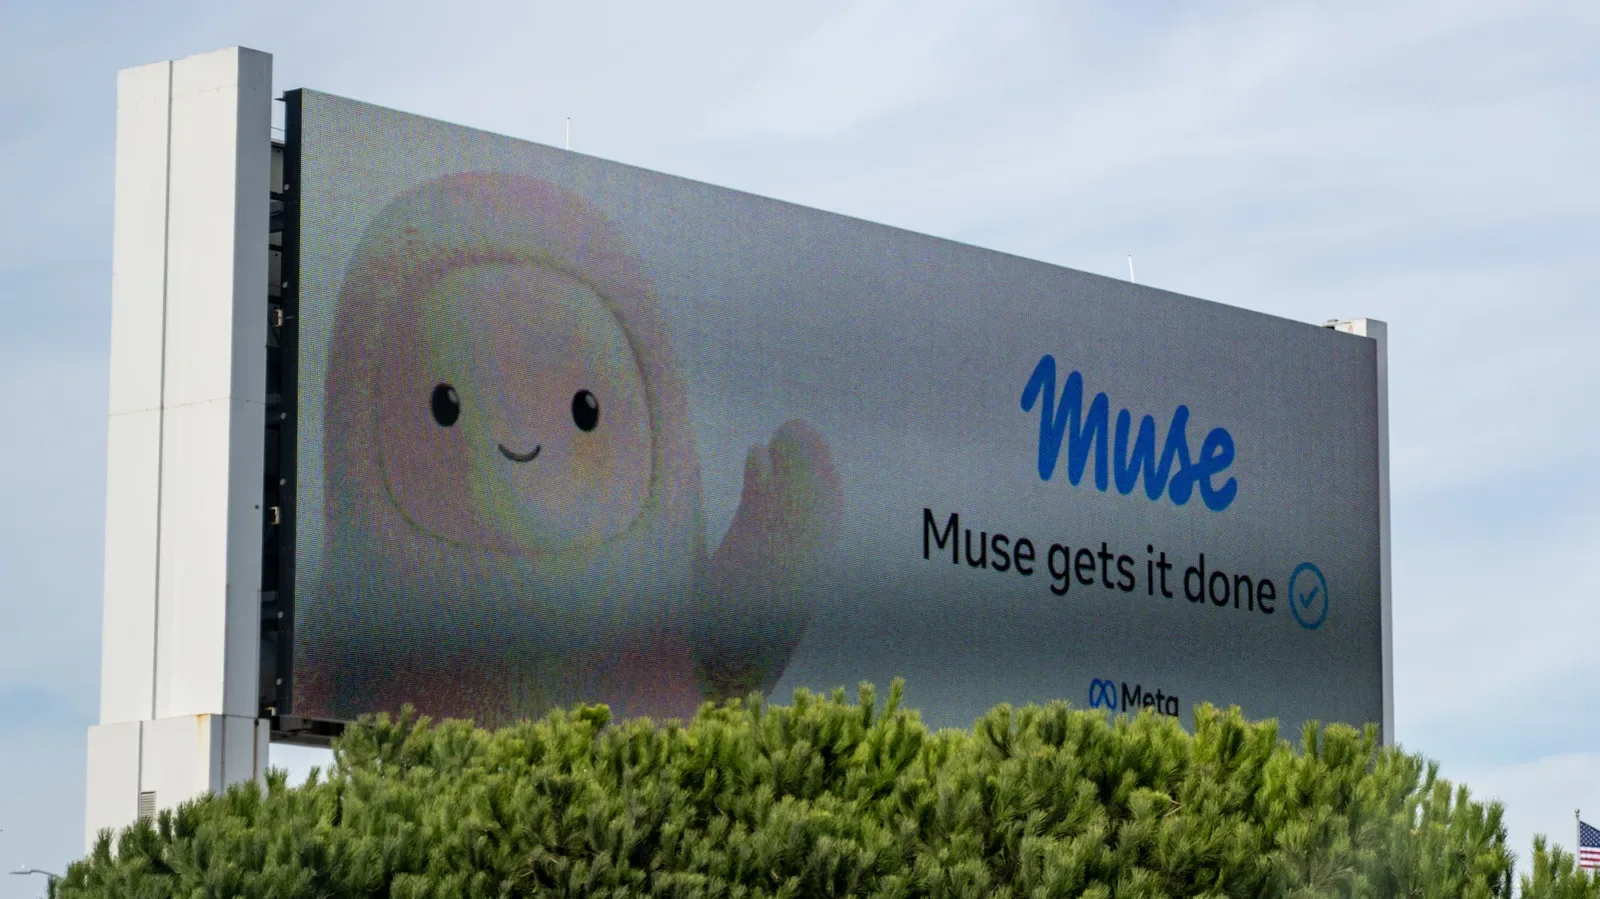
At the same time, the company used the quarter to make a forceful case that artificial intelligence is becoming central to its next phase. Meta highlighted Muse, its new personal AI agent, alongside a Muse-infused gadget and a new range of Meta-branded eyeglasses. The contrast is striking: the company is absorbing major costs tied to allegations over the safety and design of its existing platforms while promoting more personal, persistent and potentially more data-aware AI products.
The numbers: strong sales, distorted profitability
Meta reported $64.6 billion in quarterly revenue, stated as a 26% increase year over year. That beat the $63.4 billion analyst expectation. Net income was $9.86 billion, reported as up 264%, and diluted earnings per share came in at $3.83.
Revenue and earnings per share answer different questions. Revenue is the money a company brings in from its business activities before expenses. Earnings per share, commonly shortened to EPS, takes profit attributable to shareholders and divides it across outstanding shares. Investors often follow EPS closely because it combines sales, costs and share count into one per-share figure.
In this case, the gap between a revenue beat and an EPS miss is explained largely by the settlement charge. It is important not to treat Meta’s alternative operating-income figure as the same thing as its reported result. The reported number includes the quarter’s actual recognized cost; the higher figure describes what operating income would have been without that specified $9.89 billion charge. Both figures are useful, but they serve different purposes.
The market’s immediate 5% after-hours move indicates that traders did not interpret the lower EPS figure as a straightforward sign of weakening demand in Meta’s core operation. Revenue exceeded the consensus estimate, and the settlement appears to be an identifiable legal expense rather than a routine operating cost. That does not erase the financial or reputational significance of the settlement. It does explain why investors may separate the charge from their assessment of the company’s underlying sales momentum.
What the settlement was about
In August, Meta reached an $18 billion settlement with 52 state attorneys general. The claims described in the case included allegations that Instagram was designed with addictive features, that young users were knowingly exposed to serious harms, and that the public was intentionally misled about platform safety, among other allegations.
The settlement’s accounting effect landed directly in the third-quarter discussion. Meta attributed $9.89 billion in costs during the period to the agreement. A settlement total and a quarterly expense are not necessarily identical figures: the former describes the overall agreement, while the latter is the amount the company says affected this reporting period.
Separate from the multistate settlement, a New Mexico judge ordered Meta to pay $25 billion after a jury found the company liable last month for deceiving users about Facebook’s data-privacy and content-moderation policies. The order arrived hours before the earnings report. The supplied information does not establish how, or whether, that separate ruling is reflected in the reported third-quarter figures. It should therefore be considered a distinct development, rather than folded automatically into the $9.89 billion settlement charge.
For users, creators and businesses that depend on Meta’s platforms, the practical issue is broader than a single quarterly line item. The legal developments put renewed attention on the company’s privacy practices, moderation policies and safeguards for younger people. Financial markets can view a settlement as a discrete cost; platform users may instead see it as part of a continuing question about whether product growth, engagement goals and user protection are being balanced responsibly.
Muse becomes the centerpiece of Meta’s AI push
Meta also used the earnings release and call to emphasize an AI reset built around Muse. The company introduced the product last month and described it as a personal AI agent intended for broad use. At Meta Connect, Muse was represented by an animated character and integrated into multiple software and hardware efforts.
An AI agent is different from a one-off prompt tool in the way it is presented here. The stated ambition is for software that can understand a person’s goals and help carry work forward across tasks, rather than only return an isolated answer. That is an ambitious product category, particularly where users may ask an agent to handle sensitive plans, relationships, finances, creative work or business activity.
Meta chief executive Mark Zuckerberg said the company had reached “major milestones” toward providing personal superintelligence, pointing to Muse and Muse Wonder, called the company’s first frontier model. In AI discussions, a frontier model generally refers to a highly capable model positioned at the leading edge of a developer’s work. The term is a description of capability ambitions, not a guarantee that a product can reliably perform every task a user gives it.
Zuckerberg said more than 10 million people in the United States and Canada have set up Muse agents. He also said 25% of people who set up an agent use Muse daily. Those are company-provided adoption measures, and they should be read carefully. Setting up an agent measures initial onboarding, while daily use measures recurring activity among that setup group. Neither number by itself tells readers how much time people spend with Muse, what tasks they complete, or whether they remain active over longer periods.
Still, the figures give Meta a concrete early engagement claim for a product that is clearly being positioned as more than a chatbot. Zuckerberg described the company’s goal as giving each person a capable agent that understands their objectives and can help with tasks such as saving time or money, creating things, building a business and improving relationships.
Why the AI strategy and legal scrutiny now intersect
Meta’s third quarter is a reminder that AI rollouts are not happening in a vacuum. A company facing scrutiny over data privacy, content moderation and alleged harms to young users is now asking users to embrace an agent designed to understand goals and assist across parts of daily life. The source material does not detail Muse’s data practices, privacy controls or safety protections, so those specifics cannot be assumed. But they are obvious questions users should ask as agent-based products expand.
Useful questions include what information an AI agent can access, whether it retains context between interactions, how a user can review or delete that information, and what protections apply when an agent is used by or around younger people. These are not claims about Muse’s implementation. They are practical considerations for any personal agent whose value proposition rests on knowing more about the person using it.
The broader entertainment and creator economy is also likely to watch the rollout closely. Meta’s products sit at the intersection of social communication, digital identity, advertising and hardware. A successful personal agent could change how people discover content, make media, message contacts or interact with wearable devices. But the same integration can increase the importance of transparent controls and clear explanations when AI tools influence what people see or do.
Concerns over AI likeness and consent are already affecting public-facing creative work. That wider debate is reflected in a recent case involving AI video likeness and political messaging. Meta’s results do not establish a direct connection to that situation, but both stories underline how quickly questions of agency, representation and control are moving from technical discussions into public culture.
What investors appeared to see
The after-hours share-price increase does not mean the legal matters are insignificant, nor does it predict the stock’s future direction. It does show that the immediate market reaction gave considerable weight to revenue strength, the disclosed explanation for the EPS miss and Meta’s AI narrative.
For Meta, the next challenge is execution on both fronts. The company will need to show whether Muse can retain users beyond setup and translate its early use figures into sustained value. It will also need to manage the consequences of major legal actions involving platform safety and privacy. Zuckerberg’s remarks emphasized that ideas must be matched by execution. The quarter makes that a particularly apt standard: Meta is trying to demonstrate that it can build a new generation of personal AI products while facing the cost and accountability questions generated by its existing social platforms.