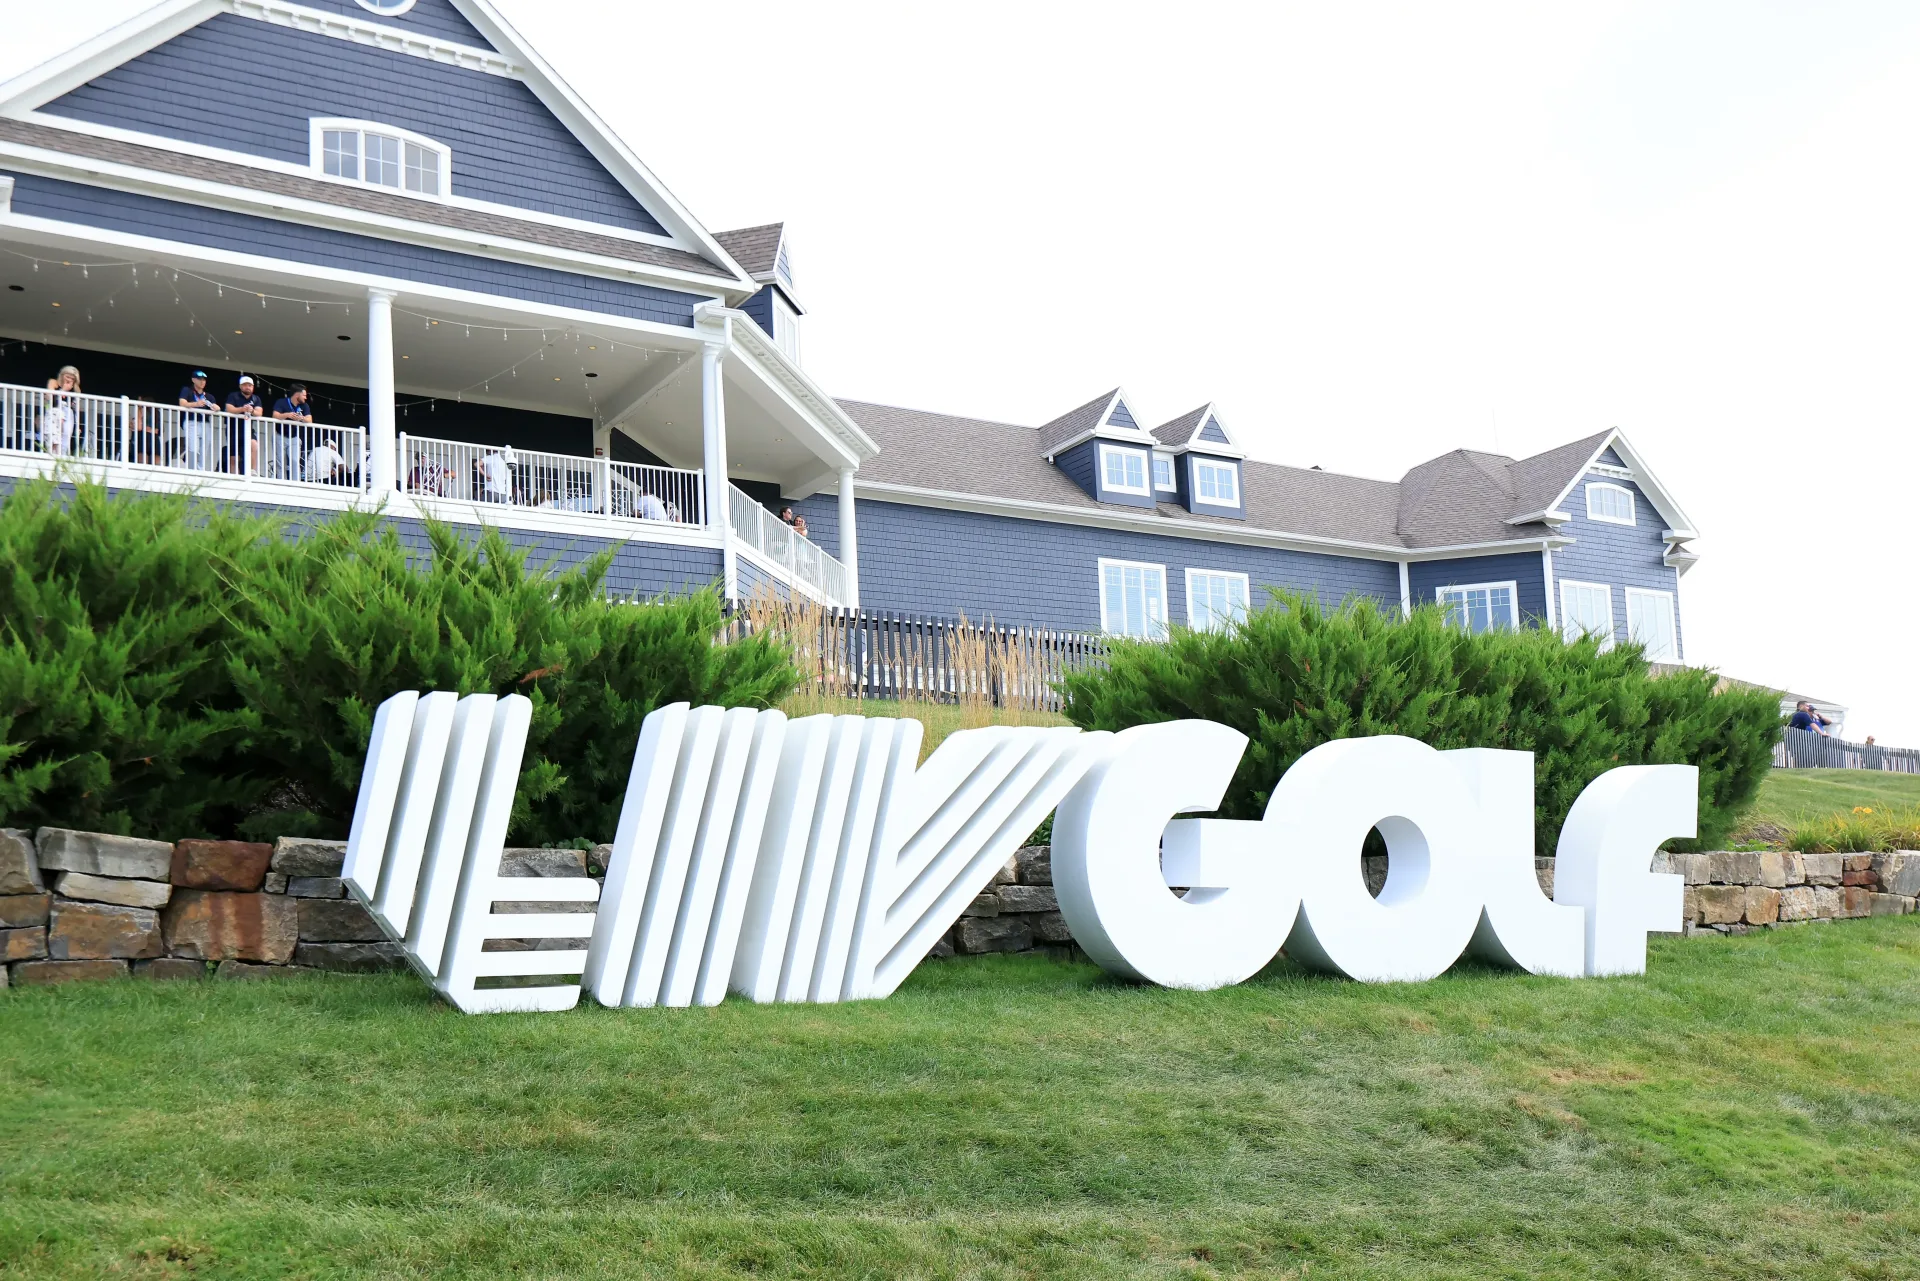
LIV Golf says it intends to liquidate its assets and wind down the business after negotiations around a proposed rescue investment failed to produce an agreement among the involved parties. The outcome puts an abrupt end point on one of professional golf’s most heavily funded and disruptive recent ventures, while leaving important practical questions around its events, players and U.S. media arrangement unresolved.
The league entered voluntary Chapter 11 proceedings in the U.S. Bankruptcy Court for the District of New Jersey after Saudi Arabia’s Public Investment Fund, its principal backer, ended funding in April 2026. The Public Investment Fund had invested more than $5 billion in LIV Golf. A proposed recapitalization with BC Partners Advisors was intended to provide a potential route forward, but the parties did not reach a consensual resolution of outstanding deal terms.
BC Partners Credit had proposed a $300 million investment. It said it supported a transaction designed to align player and investor interests and offer a sustainable future for the league, but that mutually acceptable terms could not be finalized among the stakeholders.
What LIV Golf’s wind-down announcement actually means
In ordinary business language, liquidation means converting a company’s assets into money to address its obligations and bring its affairs to a close. It is distinct from a recapitalization, which is a transaction meant to change or refresh a company’s financial foundation—often by bringing in new capital, revising debt arrangements, or both—so that it can continue operating.
Chapter 11 is commonly associated with reorganization rather than immediate closure. It provides a court-supervised framework in which a company can seek agreement with creditors and other stakeholders on a plan for its future. In LIV Golf’s case, the proposed recapitalization did not yield the consensus needed for that path. The league’s stated next step is liquidation and an operational wind-down.
That does not mean every possible transaction has been ruled out. LIV Golf said it remains open to alternatives with third parties that could maximize value. That is a meaningful qualifier, but it is not an announced deal, a promise of continued competition, or a timetable for a revival. Until a concrete alternative is identified and agreed, the stated plan is to wind down.
A league built as a challenge to golf’s established order
LIV Golf was founded in 2021 by a group of professional golfers led by Phil Mickelson and Greg Norman. It emerged from dissatisfaction with the PGA Tour, the sport’s established leading tour, and its arrival quickly became one of golf’s biggest business stories. The scale of backing from Saudi Arabia’s Public Investment Fund made LIV unusual: more than $5 billion went into the venture before that funding ended.
That financing supported an ambitious attempt to establish a global competition platform and reach a broader audience. CEO Scott O’Neil characterized the project as an effort to bring new, younger and more diverse fans to golf. He described the league’s run as demanding and challenging but rewarding, and said he hoped the memories created by it would encourage a new generation to follow and play the sport.
Related coverage includes LIV Golf Plans Liquidation After $300 Million Rescue Deal Falls Apart.
The current season’s top-ranked LIV golfers included Jon Rahm, Bryson DeChambeau, Joaquin Niemann, Lucas Herbert, Tyrrell Hatton, Thomas Detry, Anthony Kim and Sergio Garcia. Their presence underscores the central tension now facing the business side of the story: the league featured prominent players, but an operation with elite talent still requires a viable agreement among its financial stakeholders to continue.
The broadcast question remains open
One immediate area to watch is media rights. In January 2025, Fox Sports and LIV Golf announced a multiyear agreement for live U.S. coverage. Fox carried the league’s 14-tournament global schedule, with events taking place across the United States, Asia, Australia, Europe and Latin America. Before that arrangement, LIV tournaments had aired on The CW.
A multiyear agreement does not by itself answer what happens when the sports property on the other side intends to liquidate. The available information does not establish the status of the Fox arrangement, whether any remaining obligations will be performed, or how the deal may be treated during the wind-down. A Fox Sports representative did not immediately provide comment.
For viewers, the important distinction is between a rights announcement and an assurance that future events will occur. The former is already known; the latter has not been established. Fans should therefore avoid treating the earlier television agreement as confirmation of a future LIV schedule while the business works through liquidation and any possible third-party alternative.
Sports-rights deals are often discussed as if they are simple programming purchases. In reality, the value depends on a working sports organization being able to stage events, deliver a usable schedule and maintain the rights it agreed to supply. When the underlying league’s corporate future changes, questions about programming naturally follow—but the information available here does not provide final answers.
Why the failed deal matters more than the headline number
The proposed $300 million commitment is a striking figure, yet the bigger issue is that a rescue proposal needs terms acceptable to multiple parties. A new investor may seek protections, control rights or financial terms that others must accept. Players, existing investors, creditors and the company can each have different interests in a reorganization. A deal can therefore have support in principle and still fail over unresolved details.
LIV Golf’s statement points directly to that problem: the relevant parties could not resolve certain outstanding terms by mutual consent. Neither the league nor BC Partners Credit detailed those terms in the information available. It would be speculation to assign the impasse to a particular party or issue.
What is clear is the sequence: the Public Investment Fund ended funding; LIV pursued a Chapter 11 recapitalization; BC Partners Credit proposed an investment; the parties did not complete mutually acceptable terms; and LIV announced its intent to liquidate. That sequence explains why the current moment should not be reduced to a simple question of whether there was investor interest. There was a proposed investment. The missing ingredient was an agreement everyone necessary to the transaction could live with.
What to watch next
- Whether an alternative buyer or deal emerges: LIV has explicitly left the door open to value-maximizing proposals from third parties. No such alternative has been announced.
- How the wind-down is administered: Gibson, Dunn & Crutcher is lead legal counsel, with Cole Schotz serving as co-legal counsel. David Orlofsky of AlixPartners is chief restructuring officer, Ducera Partners is investment banker, and C Street Advisory Group is strategic communications adviser.
- The status of competition and broadcast plans: The known Fox agreement covered LIV’s 14-event global schedule, but no further operational outcome has been confirmed in connection with the liquidation plan.
- Player implications: LIV’s standings included several recognizable names, yet the information released does not set out individual player arrangements or next steps. Any claims about destinations, contracts or future participation would go beyond what has been disclosed.
A sharp reminder about the business underneath the spectacle
LIV Golf’s planned wind-down is a reminder that building a sports league is not only about attracting star competitors, staging international events or securing television exposure. Those are all significant pieces. But a league also needs a durable capital structure: enough funding, workable obligations and agreements that reconcile the interests of the people whose approval is needed.
The league’s story included global ambitions, a 14-tournament schedule and a roster led by high-profile golfers. It also included an extraordinary level of backing from its main investor. Yet once that funding stopped, the proposed replacement transaction did not close. The result, at least for now, is an announced liquidation rather than a reorganization.
For anyone following the wider intersection of audiences, platforms and media-business strategy, this is another example of how quickly an entertainment product’s public-facing plan can change when financing and deal terms fail to align. That broader platform pressure is also visible in the continuing debate over how digital platforms shape attention through autoplay and recommendations, though LIV’s immediate issue is not an audience-policy dispute; it is the inability to complete its proposed restructuring transaction.
LIV Golf’s own message leaves a narrow opening for a different outcome if a third party presents a value-maximizing option. For now, however, the company has stated plainly that it expects to liquidate assets and wind down its business. The next meaningful development will be an actual agreement, court-related update or operating-plan clarification—not merely the possibility that one could emerge.