Legendary Entertainment has reportedly returned with a takeover proposal for Lionsgate, renewing a piece of Hollywood dealmaking speculation that could have major implications for two companies built around recognizable film franchises.
The reported offer values Lionsgate at $3.5 billion including $1.9 billion in debt. That distinction matters: it describes the value assigned to the whole business, not simply the cash value paid to Lionsgate shareholders. Representatives for both Legendary and Lionsgate declined to comment, so the existence, terms, timing and ultimate fate of any proposal remain unconfirmed by the companies themselves.
Investors nevertheless reacted quickly. Lionsgate shares rose more than 15% on Tuesday following the report. A market move is not proof that a transaction will happen, but it does show that investors see some possible value in a combination—or at least a renewed chance that a competitive process could emerge.
What is reportedly on the table
At the center of the report is a bid from Legendary, the company associated with the Dune franchise and A Minecraft Movie, for Lionsgate Studios. Lionsgate’s film brands include John Wick, The Hunger Games and Saw. The company’s studio operation includes television and film production, distribution divisions, and a library of more than 20,000 titles.
One practical rationale for Legendary is distribution. Legendary is a production company, while Lionsgate Studios has its own distribution operation. A merger could therefore give Legendary a route to distribute its films itself rather than relying on an outside distribution partner. In plain terms, self-distribution means a company controls more of the process that takes a finished movie into theaters and onward through its commercial life.
That control can be strategically attractive because the distribution side is where release planning, marketing coordination, relationships with exhibitors and the handling of a film library sit. It does not automatically make every release more successful, and no specific operational plan has been announced. But it explains why Lionsgate could offer more than a catalogue of familiar intellectual property to a prospective buyer.
The Starz separation reshaped the target
The reported approach follows a significant corporate change at Lionsgate. Starz formally separated from Lionsgate in May 2025, after which Lionsgate Studios became a separately traded entity. The split left the studios business more clearly defined as an entity containing the film and television production and distribution operations plus the extensive content library.
That narrower structure is important context for any potential transaction. A buyer considering Lionsgate Studios would be evaluating a studio-focused package rather than the former combined company that also included Starz. The separation does not make a sale inevitable, but it makes the asset under discussion easier to describe: production capabilities, distribution infrastructure and a deep catalogue, alongside the financial obligations attached to the business.
Related coverage includes Legendary Reportedly Returns With $3.5B Lionsgate Takeover Offer.
Starz remains relevant to the broader Lionsgate story even after the separation. Readers following the premium network’s distribution footprint can also see how Starz returned to Verizon Fios under a new carriage agreement. That is a separate development, not evidence of a Lionsgate-Legendary deal, but it underlines why distinguishing the post-separation companies is useful.
How the $3.5 billion figure should be read
The reported $3.5 billion valuation includes $1.9 billion in debt. This is commonly described as an enterprise value: a way to assess the value of a business that accounts for both its equity and debt. It should not be read as a simple $3.5 billion payout to stockholders.
Lionsgate reported $425.8 million in cash and equivalents and total debt of $1.9 billion as of June 30. Cash and equivalents generally refers to cash on hand and highly liquid assets, while debt refers to the company’s outstanding borrowing obligations. Those figures are relevant because an acquirer must consider not only a studio’s franchises and future revenue potential, but also the balance sheet it would be taking on or refinancing.
That is particularly useful context when interpreting the reported valuation. Debt is not a side note in a takeover discussion; it can shape financing, negotiations and how prospective buyers assess the economics of a deal. The available information does not disclose the structure of Legendary’s reported offer, whether it is cash, stock or some combination, nor does it reveal any proposed financing arrangement. It also does not establish whether Lionsgate’s board is considering the proposal.
Lionsgate’s recent financial picture is mixed
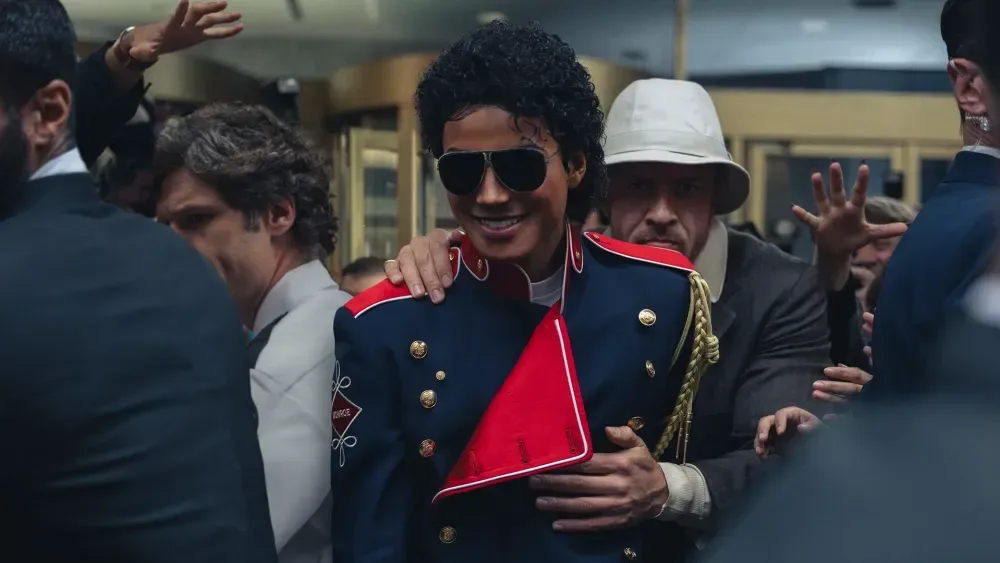
Lionsgate’s latest reported quarter contained both a substantial improvement and a clear pressure point. For the June 2026 quarter, overall revenue rose 48%, while the movie segment generated $105 million in income. The performance was driven by Michael, the Michael Jackson biopic described as Lionsgate’s biggest box-office film to date and the first biopic to pass $1 billion in theatrical release.
At the same time, the company recorded a quarterly net loss attributable to shareholders of $28.8 million. That was much better than the $94 million loss reported a year earlier, but it remained a loss. Its television division also saw revenue and profit decline.
The distinction is worth keeping in view. A hit movie can transform a quarter for a film segment, but a buyer has to assess the broader company across several businesses and over a longer period. The reported figures point to a studio with evidence of strong theatrical upside and major franchise assets, while also showing uneven performance across divisions and a meaningful debt load.
For fans, this is not a reason to assume release schedules, creative teams or franchise plans will immediately change. No transaction has been announced, and corporate deals can take many paths: a proposal may be rejected, altered, superseded by another bid or never reach a signed agreement. The clearest near-term event is Lionsgate’s scheduled fiscal 2027 second-quarter results, covering the three months ended September 30, 2026, due after market close on November 5.
Legendary’s ownership context
Legendary’s own ownership changed in recent years. In 2024, it bought out the stake held by Chinese conglomerate Dalian Wanda Group. The resulting arrangement left Legendary and private-equity firm Apollo Global Management in control. Apollo had acquired a stake in Legendary in 2022 for $760 million.
That background helps explain why Legendary is positioned as a potential buyer rather than solely a production partner. It also puts the reported approach in a longer sequence: Legendary had explored a possible acquisition last year and had reached out about a potential partnership with Lionsgate Studios after the Starz split.
A partnership and a takeover are materially different ideas. A partnership could involve limited cooperation around financing, production or distribution. A takeover would seek control of the company itself. The current report concerns the latter, but neither side has publicly detailed a transaction and no agreement has been confirmed.
Other interest does not yet equal a bidding contest
Banijay and Mediawan have also been identified as companies with interest in Lionsgate, although neither had submitted a formal takeover offer. Banijay recently merged with the United Kingdom’s All3Media and is now known as Banijay Entertainment.
That interest could matter in negotiations, but it should not be overstated. Interest, exploratory conversations and a formal bid are different stages. The supplied information establishes a reported new offer from Legendary and identifies other companies that have shown interest without making formal offers. It does not establish a live auction, a deadline, competing terms or a preferred buyer.
What to watch next
The next several signals will be more informative than the initial share-price reaction. Lionsgate’s November 5 earnings report should provide an updated view of operating performance, cash and debt. Any public filing or company statement could clarify whether a proposal exists and whether talks are active. Until then, the central facts remain limited: a reported $3.5 billion valuation including debt, a sharp move in Lionsgate’s shares, a strategically plausible distribution rationale for Legendary, and no public confirmation from either company.
For the entertainment business, the story is ultimately about control of a studio platform. Legendary brings recent blockbuster credentials; Lionsgate brings established franchises, a large library and distribution capability. Whether those ingredients lead to a completed deal is still uncertain. For now, this is a reported bid—not a finished acquisition—and the distinction is the most important one.