Starz’s third-quarter 2026 report offered a compact but consequential snapshot of a standalone streaming-and-TV business trying to improve its economics without relying on a single route to viewers. For the three months ended September 30, Starz reported $322.4 million in revenue and a $34.8 million net loss. The loss was narrower than the $52.6 million recorded in the comparable quarter a year earlier, while revenue came in above the $319.5 million analyst consensus expectation.
The company also reported a diluted loss per share of $2.02, better than the $2.96 loss per share expected by analysts. “Better,” in this case, does not mean Starz is profitable: it means the reported loss was smaller than the market had forecast. That distinction matters when reading entertainment-company earnings, where investors may weigh progress toward a plan as closely as the raw bottom line.
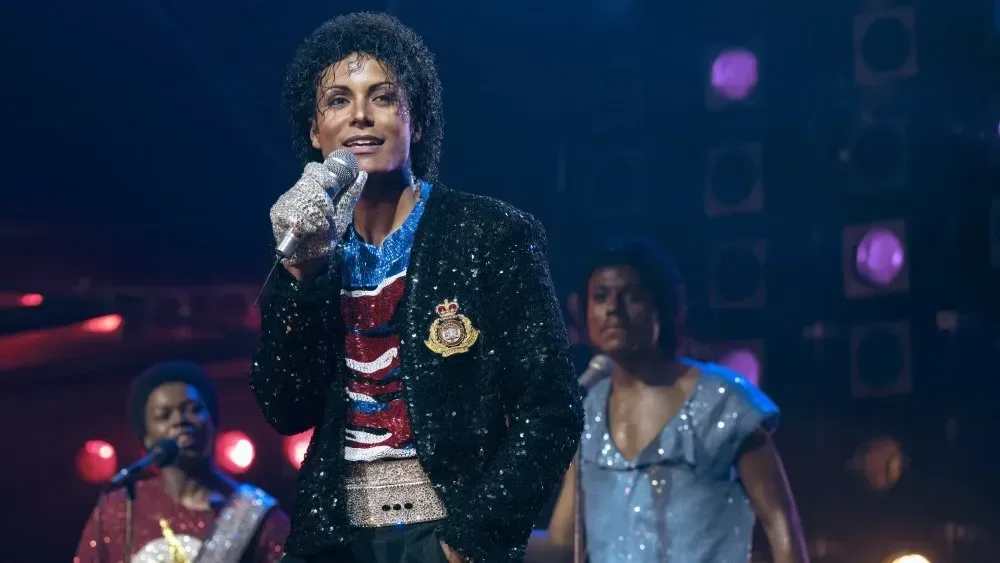
Programming was central to the quarter’s story. Lionsgate’s Michael debuted on Starz on August 10 and has since become the network’s best-performing Pay 1 title in its history. The report does not provide a viewership figure or define the measurement behind that ranking, so the record should be understood as Starz’s own performance designation rather than a directly comparable audience total across the wider streaming market.
Still, the result gives Starz a clear example of a high-profile film lifting its premium-window offering at a moment when it is seeking steadier revenue and more flexibility in distribution. The title’s Michael Jackson subject matter also arrives amid continuing public attention around the Jackson estate; readers looking for related context can see this report on Paris Jackson’s estate-management fee dispute.
What the quarterly numbers say
Starz divided the revenue picture into two broad buckets. OTT revenue reached $226.6 million, up 1.7% from $222.8 million in the prior-year period. OTT, or over-the-top, refers to video delivered over the internet rather than through a conventional cable or satellite channel. It can include a direct streaming service as well as digital distribution arrangements, depending on how a company reports its business.
Chief financial officer Scott Macdonald said the growth rate would have been 3.2% on a pro forma basis after accounting for a strategic change to the company’s Canadian operations. Starz moved those operations to a content-licensing arrangement in the fourth quarter of 2025. Pro forma is a way of presenting results as though a business change had already applied to an earlier comparison period. It can help show underlying movement without a structural shift distorting the year-over-year percentage, but it is not a replacement for the reported figure. Here, the reported OTT increase was 1.7%; the adjusted comparison cited by management was 3.2%.
Linear TV and other revenue totaled $95.8 million, down from $98.1 million a year earlier. Linear TV generally means scheduled, traditional channel viewing: viewers tune into programming at a particular time rather than choosing a title from an on-demand library. The decline was partly offset by higher distribution revenue, which Starz attributed to Fightland, described as the company’s first owned original series.
That ownership point is more than a corporate footnote. When a service owns an original program, it may have more control over how the title is used and monetized than it would with a licensed show. The specific financial benefits and rights arrangements were not detailed in the quarter’s results, but Starz president and CEO Jeffrey Hirsch framed increased ownership as a source of prospective financial upside. For an entertainment business looking to establish a durable revenue base, ownership can be a strategic lever alongside subscriber growth, licensing, bundles and conventional channel distribution.
‘Michael’ and the meaning of Pay 1
A Pay 1 window is the first premium subscription-TV or streaming period after a film’s earlier release stages. In practical terms, it is the point at which a movie becomes a major draw for a premium service’s subscribers and distribution partners. A strong Pay 1 performer can matter because it gives a service a prominent reason to market its library, retain viewers, attract attention through add-on channels and strengthen the perceived value of its programming slate.
Starz says Michael is now its top Pay 1 title ever, a notable result given that the film had only been on the service since August 10 during a quarter ending September 30. What cannot be concluded from the information provided is precisely why it led—whether through starts, completed views, subscriber activity, engagement, revenue contribution or another internal performance metric. Nor do the supplied results establish a direct dollar amount generated by the movie.
The more measured takeaway is that Starz has identified the release as evidence supporting its programming strategy. Hirsch described the company as using a portfolio approach to programming, arguing that it creates a more durable revenue base. A portfolio approach, in this setting, means not pinning the business on one kind of program or one method of reaching viewers. The Q3 results point to several pieces of that approach at once: a prominent licensed film, an owned original series, internet-delivered revenue, traditional TV revenue and distribution income.
Standalone Starz is emphasizing reach, not ownership of every platform
The quarter came after Starz separated from Lionsgate in May 2025. As a standalone company, its central challenge is not simply to have shows and films that viewers recognize. It must also make those titles work across an evolving set of access points while managing the financial realities of a business that remains loss-making.
Hirsch’s planned remarks for the earnings call made the company’s distribution philosophy especially plain: Starz does not believe it must control the entire consumer ecosystem to grow. Instead, it is pointing to traditional distribution, add-on subscriptions, strategic partnerships and new bundles as multiple ways to reach audiences.
That language is significant because it avoids treating direct-to-consumer streaming as the only meaningful destination. An add-on subscription is typically a premium service purchased through another platform or provider, while a bundle combines services or offerings into one package. Neither model is automatically superior in every circumstance. Their relevance here is that they can broaden access to Starz without requiring every viewer relationship to begin and end inside a fully owned app environment.
For viewers, this strategy may mean that the question is less “Where is the one definitive Starz destination?” and more “Which subscription route offers access?” For Starz, it potentially creates several paths to distribution revenue and audience reach. The tradeoff, as an analytical matter, is that a broader partner-led model can involve sharing parts of the customer relationship and economics with distributors. The supplied results do not quantify that tradeoff, but Hirsch’s comments make clear that Starz considers flexibility worthwhile if it advances the core business.
Why the earnings beat is useful, but not a finish line
The numbers exceeded analyst expectations on both revenue and loss per share, and the year-over-year net-loss comparison improved. Those are constructive signals. Yet the report also shows why the next stage of execution matters: OTT revenue grew modestly on a reported basis, linear and other revenue declined, and the overall business still posted a net loss.
Starz’s presentation of the Canadian adjustment is particularly useful for separating two questions that can otherwise get blurred. First: what did the company report? The answer is 1.7% OTT revenue growth. Second: what does management believe growth would have looked like without the operational shift in Canada? The cited pro forma answer is 3.2%. Readers should keep both in view. Reported results are the formal record of the quarter, while adjusted figures are intended to aid comparisons across changed business structures.
Likewise, the success of Michael is a meaningful programming data point but not, by itself, a complete operating blueprint. A record-performing Pay 1 title can enhance a quarter and validate a content bet, but the company’s stated strategy depends on a broader mix: owned series such as Fightland, licensing arrangements, partnerships, add-on offerings, bundles and continued attention to the economics of its programming portfolio.
What to watch from here
- OTT momentum: Whether future results show sustained reported growth, and how often adjusted growth differs from the official year-over-year figure.
- Programming ownership: Starz has said increased ownership can provide financial upside. Future disclosures may clarify how that strategy affects revenue, distribution and costs.
- Distribution mix: The company is explicitly pursuing traditional channels, add-on subscriptions, partnerships and bundles rather than a one-platform-only approach.
- Linear-TV pressure: Q3’s linear TV and other revenue declined year over year, even as distribution income helped soften that movement.
- Strategic discipline: Hirsch said any prospective transaction would need to accelerate Starz’s strategy and produce more value than the company believes it can create independently.
Starz’s Q3 report is therefore best read as progress within a still-active transition. The company beat the immediate consensus forecast, narrowed its loss, delivered modest OTT growth and gained a standout Pay 1 success with Michael. The longer test is whether that combination becomes repeatable: a programming slate that performs, ownership that improves economics and distribution choices that reach audiences wherever they prefer to watch.